Key takeaways
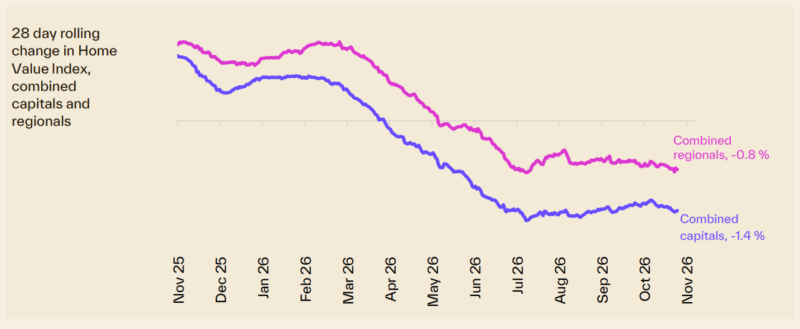
Property values continue to decline. Combined capital city dwelling values fell 1.4% over the past month and are now 6.1% lower than a year ago.
Sydney and Melbourne are experiencing significant corrections. Sydney values are down 10.6% annually, while Melbourne values have fallen 8.2%.
Auction clearance rates have weakened sharply. The preliminary combined capital city clearance rate fell to 44%, its lowest level since April 2020.
Properties are taking longer to sell. The national median selling time has increased to 41 days, compared with 26 days a year ago.
Buyers have greater negotiating power. Slower sales, weaker clearance rates and cautious sentiment are creating opportunities for well-prepared purchasers.
Rental market conditions are easing. The national vacancy rate has risen to 2.3%, while rental growth is slowing across many capital cities.
Rental yields are improving. Combined capital city gross rental yields have reached 3.77%, their highest level since May 2015.
Our property markets remain fragmented. Different cities, suburbs and price segments are performing differently, reinforcing the importance of careful property selection.
Long-term fundamentals remain important. Australia's underlying housing shortage continues to support the longer-term outlook for well-located, investment-grade properties.
Australia's property markets are continuing to weaken as we move towards the end of the year, with the latest figures showing that higher interest rates, affordability constraints and cautious buyer sentiment are taking their toll.
The number of new home loans fell 15.0% to 111,878 in the September quarter and is now 21.4% lower than a year ago, while the value of lending recorded its largest quarterly fall since the series began in 2002.
New investor loans fell 30.6% over the quarter to 35,301 and are down 38.5% on a year ago, as rate rises and the May Budget tax changes hit investor demand.
To help keep you up-to-date with all that's happening, below is my updated weekly analysis of data and charts as of 16th November 2026, provided by SQM Research, Cotality, and realestate.com.au.
According to Cotality, combined capital city dwelling values have fallen 1.4% over the past month and are now 6.1% lower than a year ago. Sydney has experienced the sharpest annual decline, with values down 10.6%, followed by Melbourne at 8.2%, while Brisbane has recorded a more modest annual fall of 1.8%, although its recent monthly decline suggests the market is losing momentum.
And there are further signs that buyers are becoming increasingly cautious.
Last weekend's preliminary auction clearance rate fell to just 44%, its lowest level since April 2020, despite auction volumes remaining more than 40% below the same time last year. Homes are also taking considerably longer to sell, with the national median time on market increasing from 26 days a year ago to 41 days.
Of course, we must remember that there is no single Australian property market, and even within our capital cities, different locations, price points and property types are behaving quite differently.
Interestingly, some of the more expensive segments that led the previous upswing are now experiencing the greatest pressure, while well-located, more affordable properties are generally showing greater resilience.
Meanwhile, our rental markets are also changing. National vacancy rates have risen to 2.3%, their highest level since January 2022, and rental growth is easing across many of our major capitals. However, with rents still rising while property values decline, gross rental yields across the combined capitals have increased to 3.77%, their highest level since May 2015.
Looking ahead, I expect the combination of restrictive interest rates, weaker confidence and stretched household budgets to keep a lid on property price growth in the short term. However, Australia's underlying housing shortage hasn't disappeared, and the longer-term fundamentals supporting well-located, investment-grade properties remain in place.
For strategic investors with secure finances and a long-term perspective, this changing market is also creating opportunities to negotiate more favourable terms and secure quality properties with less competition than we've seen in recent years.
As I've often said, successful property investment is about buying the right property, in the right location, at the right price and holding it for the long term.
On the auction front this week...Preliminary clearance rate dropped to 44.0%, the lowest since April 2020
Across the combined capitals, 1,888 auctions were held last week, an increase of 11.4% from 1,695 the previous week, but 41.1% fewer than the 3,204 held at the same time last year.
Auction volumes rose across most capitals, led by Brisbane, the ACT and Melbourne, although Sydney, Melbourne and Canberra remained more than 40% below year-ago levels.
See Cotality's full auction report below.
This week, Cotality also reports that:
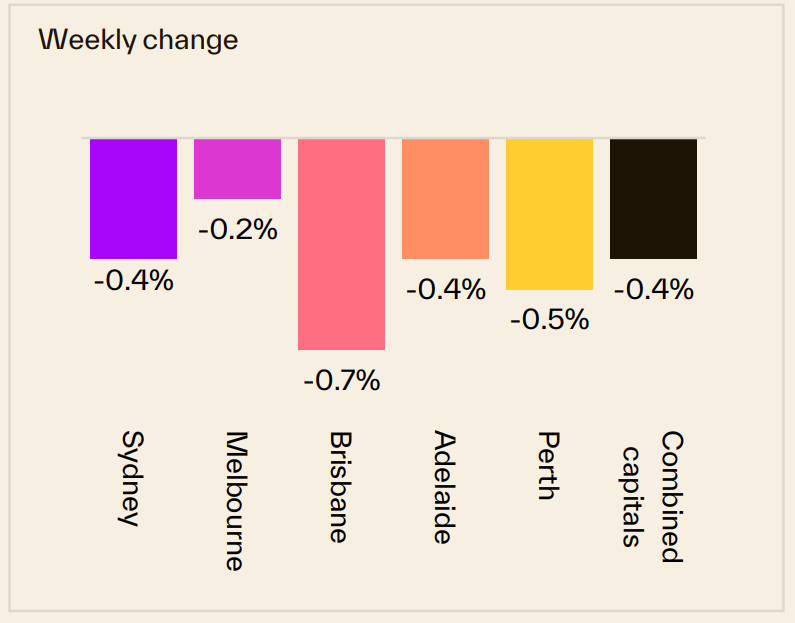
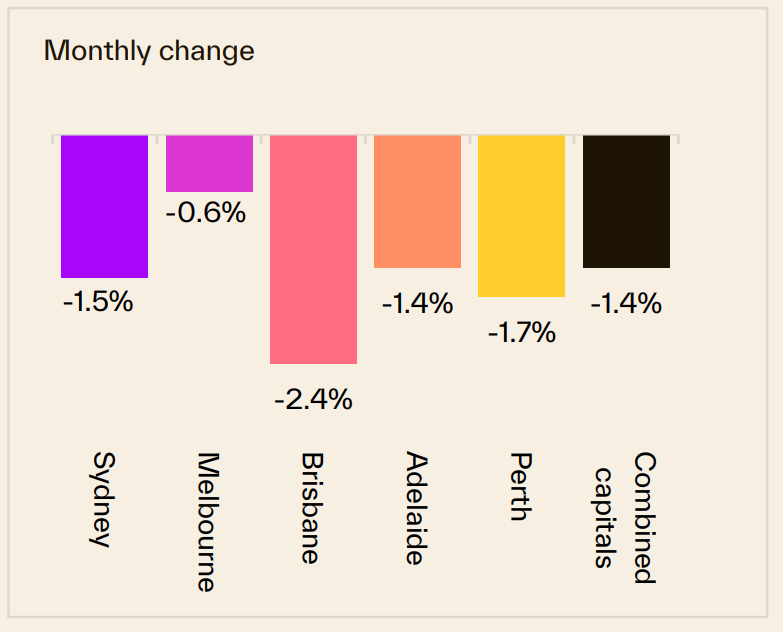
- Sydney property prices declined -0.4% over the last week, also declined -1.5% over the last month, and are -10.6% lower than they were 12 months ago.
- Melbourne property prices declined -0.2% over the last week, also declined -0.6% over the last month, are -8.2% lower compared to 12 months ago.
- Brisbane property prices declined -0.7% over the last week, declined -2.4% over the last month and are now -1.8% lower than they were 12 months ago.
Overall, Australian capital dwelling prices declined -1.4% over the last month and are now -6.1% lower than they were 12 months ago.
Clearly, the property cycle is moving on but our markets are very fragmented.
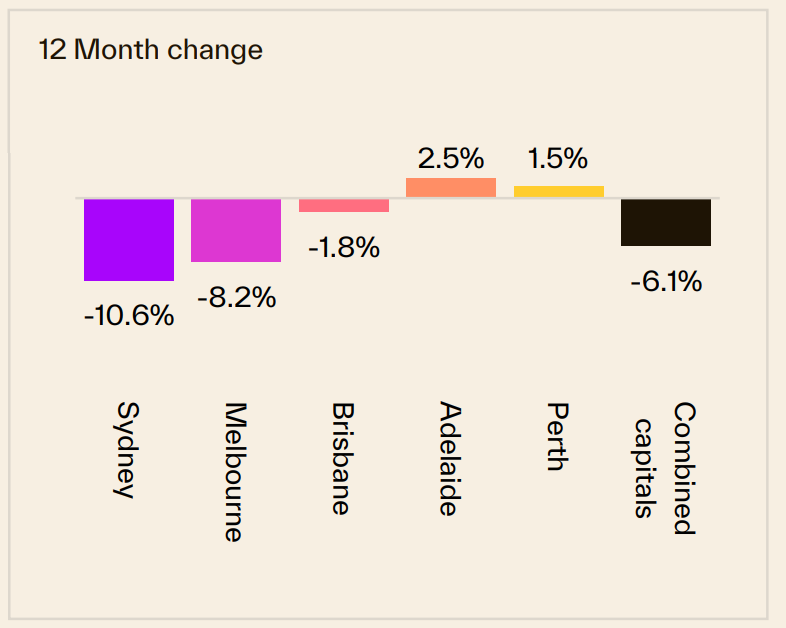
Source: Cotality November 16th 2026
Of course, these are "overall" figures - there is not one Sydney or Melbourne or Brisbane property market.
And various segments of each market are performing differently.
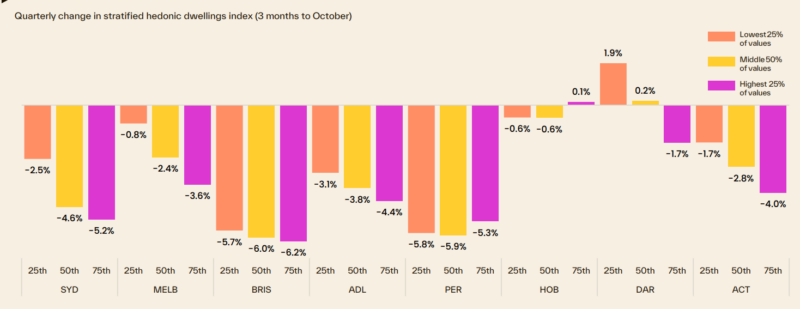
At the start of this cycle, the market's upper quartile led the upswing, but last year the lower quartile across every capital city recorded a stronger housing-value outcome than its upper-quartile counterpart. Now the more expensive properties are suffering the most.
The following chart shows how different segments of each capital city market are performing.
Current property asking prices
Property asking prices are a useful leading indicator for housing markets - giving a good indication of what's ahead.
Here is the latest data available:
Sydney
| Property type | Price ($) | Weekly Change | Monthly Change % | Annual % change |
|---|---|---|---|---|
| All Houses | 2,043.107 | 5.193 | -0.4% | -3.2% |
| All Units | 896.428 | 0.671 | 0.3% | 1.7% |
| Combined | 1,574.019 | 3.405 | -0.2% | -2.2% |
Source: SQM Research
Melbourne
| Property type | Price ($) | Weekly Change | Monthly Change % | Annual % change |
|---|---|---|---|---|
| All Houses | 1,308.329 | 1.571 | 0.7% | -0.2% |
| All Units | 686.289 | -0.994 | 0.3% | 4.0% |
| Combined | 1,112.193 | 0.932 | 0.7% | 0.7% |
Source: SQM Research
Brisbane
| Property type | Price ($) | Weekly Change | Monthly Change % | Annual % change |
|---|---|---|---|---|
| All Houses | 1,300.478 | -3.527 | -1.7% | -3.9% |
| All Units | 796.959 | -6.859 | -2.5% | -1.8% |
| Combined | 1,172.311 | -4.514 | -1.9% | -3.7% |
Source: SQM Research
Perth
| Property type | Price ($) | Weekly Change | Monthly Change % | Annual % change |
|---|---|---|---|---|
| All Houses | 1,232.287 | -2.639 | -0.5% | 3.6% |
| All Units | 750.876 | -4.223 | -1.3% | 7.2% |
| Combined | 1,105.462 | -3.103 | -0.7% | 4.2% |
Source: SQM Research
Adelaide
| Property type | Price ($) | Weekly Change | Monthly Change % | Annual % change |
|---|---|---|---|---|
| All Houses | 1,079.280 | -4.901 | -1.8% | -0.4% |
| All Units | 646.710 | 0.590 | 1.6% | 10.5% |
| Combined | 1,001.021 | -3.961 | -1.4% | 0.8% |
Source: SQM Research
Canberra
| Property type | Price ($) | Weekly Change | Monthly Change % | Annual % change |
|---|---|---|---|---|
| All Houses | 1,253.119 | 1.591 | 2.0% | -2.6% |
| All Units | 598.653 | -1.403 | -0.5% | 2.3% |
| Combined | 1,002.149 | 0.100 | 1.4% | -2.0% |
Source: SQM Research
Darwin
| Property type | Price ($) | Weekly Change | Monthly Change % | Annual % change |
|---|---|---|---|---|
| All Houses | 894.802 | -11.002 | 0.6% | 12.9% |
| All Units | 508.354 | 0.146 | -1.4% | 14.2% |
| Combined | 742.904 | -6.570 | 0.0% | 13.3% |
Source: SQM Research
Hobart
| Property type | Price ($) | Weekly Change | Monthly Change % | Annual % change |
|---|---|---|---|---|
| All Houses | 953.255 | 8.545 | 2.0% | 10.2% |
| All Units | 501.952 | 1.957 | 0.0% | 0.7% |
| Combined | 883.937 | 7.509 | 1.9% | 9.2% |
Source: SQM Research
National
| Property type | Price ($) | Weekly Change | Monthly Change % | Annual % change |
|---|---|---|---|---|
| All Houses | 1,059.201 | 6.092 | -0.2% | 0.6% |
| All Units | 659.308 | -1.590 | 0.5% | 5.9% |
| Combined | 971.875 | 4.376 | -0.1% | 1.3% |
Source: SQM Research
Cap City Average
| Property type | Price ($) | Weekly Change | Monthly Change % | Annual % change |
|---|---|---|---|---|
| All Houses | 1,507.086 | 2.628 | 0.0% | -1.9% |
| All Units | 790.452 | -0.230 | -0.2% | 2.1% |
| Combined | 1,291.701 | 1.713 | 0.0% | -1.3% |
Source: SQM Research
The value of property asking prices as a leading indicator for housing markets is quite significant.
In fact it's more valuable than median prices which can be quite misleading.
Let's delve into why this is the case and how it impacts the real estate market.
- Early Market Sentiment Indicator: Asking prices often reflect the current sentiment of sellers in the real estate market.
If sellers are confident, they might set higher asking prices, anticipating strong demand.
Conversely, if sellers are uncertain or perceive a market downturn, they might lower their asking prices to attract buyers.
This makes asking prices a real-time indicator of market sentiment, often preceding changes in actual sales prices. - Predictive of Future Price Trends: Trends in asking prices can be predictive of where the actual property prices are headed.
For example, a consistent rise in asking prices over a period can signal an upcoming rise in transaction prices. - Impact of Economic Factors: Economic factors such as interest rates, employment rates, and broader economic health influence asking prices.
For instance, changes in the Reserve Bank of Australia's policies or shifts in the job market can quickly reflect in the asking prices, providing insights into how these factors are influencing the housing market. - Regional Variations: In a diverse market like Australia's, asking prices can also provide insights into regional disparities.
For instance, the property markets in Melbourne and Sydney might behave differently from those in Brisbane or Perth. Asking prices can give early indications of these regional trends. - Influence of Supply and Demand: Asking prices are also a response to the balance of supply and demand in the market.
In areas with limited supply and high demand, asking prices tend to be higher and vice versa.
However, it's important to note that while asking prices are a valuable indicator, they should not be used in isolation.
Other factors like actual sales prices, time on the market, auction clearance rates, and economic conditions also play crucial roles in understanding the property market dynamics.
READ MORE: The latest median property prices in Australia’s major cities
Last weekend's auction report
Preliminary clearance rate dropped to 44.0%, the lowest since April 2020
Across the combined capitals, 1,888 auctions were held last week, an increase of 11.4% from 1,695 the previous week, but 41.1% fewer than the 3,204 held at the same time last year.
Auction volumes rose across most capitals, led by Brisbane, the ACT and Melbourne, although Sydney, Melbourne and Canberra remained more than 40% below year-ago levels.
The combined capitals preliminary clearance rate nevertheless declined to 44.0%, down 7.5 percentage points from the previous week's preliminary rate of 51.5%.
This was the lowest preliminary result since April 2020 and well below both the spring average to date of 50.4% and the winter average of 52.3%.
- Also read:This week’s Australian Property Market Update – Latest Data, State by State November 17th 2026
- Also read:Everything you need to know about the state of Australia’s property markets in 20 charts – November 2026

- Also read:Latest Property Price Forecasts. Australian Property Market Outlook 2026-2027: Navigating a Market Correction

- Also read:Brisbane Property Market Forecast [2026 & Beyond] – What The Olympics Decade Means for Investors.
- Also read:Melbourne property market forecast for 2026 & 2027 | Separating the fundamentals from the sentiment
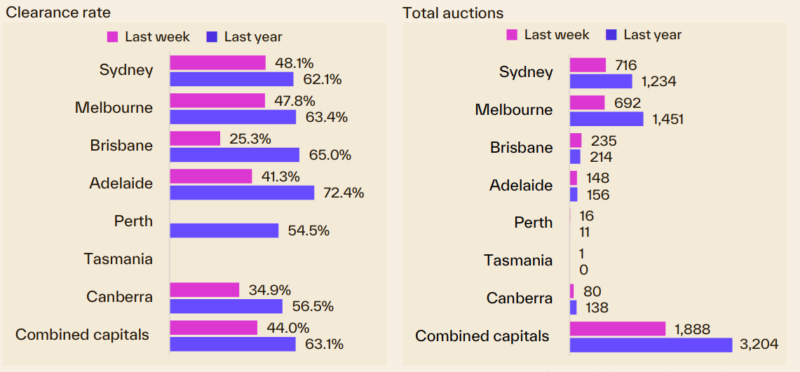
Sydney remained the largest auction market last week, with 716 homes taken to auction, up 3.5% from 692 the previous week but 42.0% fewer than a year earlier.
Its preliminary clearance rate declined by 4.2 percentage points to 48.1%, below the spring average to date of 53.7%.
Sydney remained the largest auction market last week, with 716 homes taken to auction, up 3.5% from 692 the previous week but 42.0% fewer than a year earlier.
Its preliminary clearance rate declined by 4.2 percentage points to 48.1%, below the spring average to date of 53.7%.
In Melbourne, the preliminary clearance rate fell to 47.8%, its lowest level since September 2021.
The 11.3 percentage-point decline from the previous week's preliminary rate of 59.1% left the result well below the spring average to date of 54.5%.
Auction volumes increased 16.5% to 692 from 594 the previous week but remained 52.3% below the 1,451 held at the same time last year.
Brisbane's preliminary clearance rate decreased to 25.3%, down 5.9 percentage points from the previous week's preliminary result and well below the spring average to date of 30.3%.
The rate had been below 30% in five of the previous seven weeks. By contrast, auction volumes rose 33.5% to 235 from 176 the previous week and were 9.8% higher than a year earlier, placing Brisbane among the few capitals with volumes above year-ago levels.
Adelaide's 148 auctions were little changed from 147 the previous week and 5.1% below the corresponding period last year.
The city’s preliminary clearance rate eased to 41.3%, a decline of 2.2 percentage points from the previous week's preliminary result and below the spring average to date of 44.2%
Canberra's preliminary clearance rate fell 12.2 percentage points from the previous week's preliminary result to 34.9%, well below the spring average to date of 46.5%.
The city held 80 auctions, up 17.6% from 68 the previous week but 42.0% fewer than the 138 held a year earlier.
In Perth, only eight results had been collected from 16 auctions, so no preliminary clearance rate was reported.
Auction volumes were down from 17 the previous week but up from 11 at the same time last year. One auction was held in Tasmania.
Our rental markets
Rental markets continued to loosen through spring , with the national vacancy rate rising to 2.3%, not far below the decade average of 2.4%, but still well below the pre - COVID decade average of 3.3%.
October marked the highest national vacancy rate since January 2022, one month before international
Vacancy rates were higher than a year ago across every capital city except Darwin.
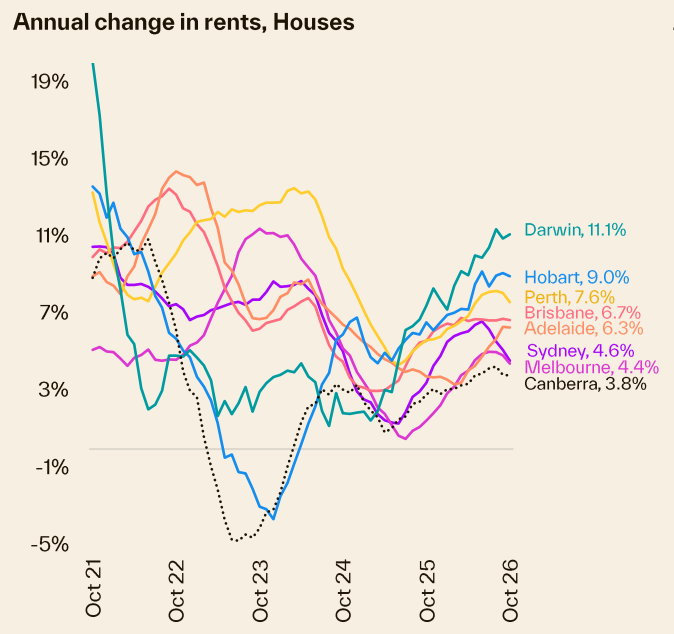
Unsurprisingly, Darwin is also recording by far the strongest annual rental growth, with house and unit rents up 11.1% and 11.7% respectively.
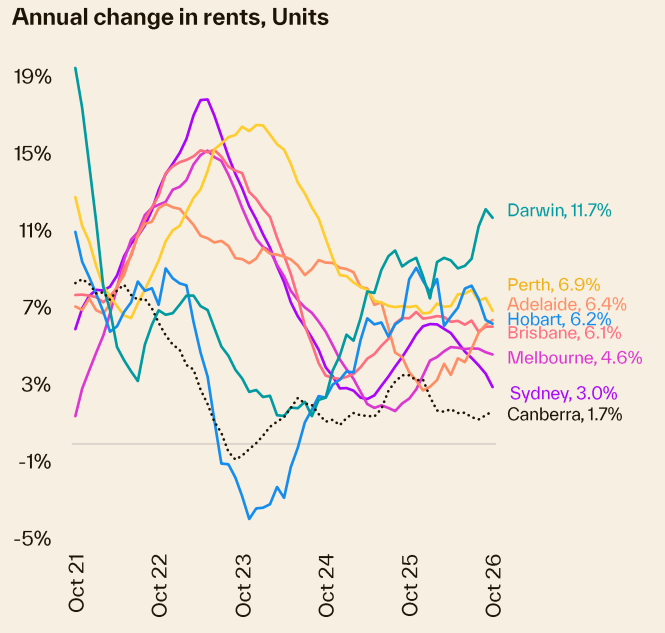
Alongside higher vacancy rates across most markets, the pace of rental growth is easing.
Most of the larger capitals recorded an easing or levelling in the annual rate of rental growth, while the 0.9% seasonally adjusted rise in national rents over the past three months was the lowest since January 2025.
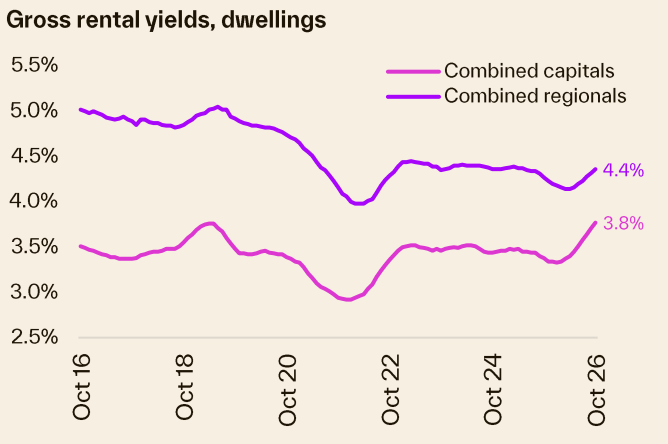
Although rental growth is slowing, rents are still rising against a backdrop of falling home values.
The net effect of rising rents and falling values is that gross rental yields are consistently trending higher.
At 3.77%, the gross rental yield across the combined capitals hasn’t been this high since May 2015.
Sydney
| Property Type | Rent ($) | Weekly change | Monthly change | 12 Months change |
|---|---|---|---|---|
| All Houses | $1,175.11 | 4.89 | 1.6% | 5.1% |
| All Units | $743.95 | 0.05 | -0.7% | 2.0% |
| Combined | $918.95 | 2.02 | 0.5% | 3.6% |
Source: SQM Research
Melbourne
| Property Type | Rent ($) | Weekly change | Monthly change | 12 Months change |
|---|---|---|---|---|
| All Houses | $824.71 | -2.70 | -0.4% | 7.4% |
| All Units | $584.02 | -1.03 | -1.6% | 3.8% |
| Combined | $685.54 | -1.73 | -1.0% | 5.7% |
Source: SQM Research
Brisbane
| Property Type | Rent ($) | Weekly change | Monthly change | 12 Months change |
|---|---|---|---|---|
| All Houses | $836.77 | -4.77 | -0.2% | 7.6% |
| All Units | $653.14 | -1.14 | 0.1% | 6.3% |
| Combined | $753.97 | -3.14 | -0.1% | 7.1% |
Source: SQM Research
Perth
| Property Type | Rent ($) | Weekly change | Monthly change | 12 Months change |
|---|---|---|---|---|
| All Houses | $894.88 | 4.12 | 0.8% | 7.3% |
| All Units | $677.70 | 6.29 | 1.9% | 4.1% |
| Combined | $805.47 | 5.02 | 1.2% | 6.2% |
Source: SQM Research
Adelaide
| Property Type | Rent $) | Weekly change | Monthly change | 12 Months change |
|---|---|---|---|---|
| All Houses | $708.25 | 1.75 | 1.5% | 4.1% |
| All Units | $549.41 | 3.58 | 0.1% | 5.4% |
| Combined | $654.94 | 2.37 | 1.1% | 4.5% |
Source: SQM Research
Canberra
| Property Type | Rent ($) | Weekly change | Monthly change | 12 Months change |
|---|---|---|---|---|
| All Houses | $799.73 | -3.73 | -0.2% | 1.0% |
| All Units | $591.56 | 3.44 | -0.2% | 2.6% |
| Combined | $684.44 | 0.24 | -0.3% | 1.6% |
Source: SQM Research
Darwin
| Property Type | Rent ($) | Weekly change | Monthly change | 12 Months change |
|---|---|---|---|---|
| All Houses | $858.17 | -3.17 | 1.2% | 12.8% |
| All Units | $636.07 | -3.07 | -3.2% | 10.7% |
| Combined | $727.23 | -3.12 | -1.1% | 11.8% |
Source: SQM Research
Hobart
| Property Type | Rent 9$) | Weekly change | Monthly change | 12 Months change |
|---|---|---|---|---|
| All Houses | $624.16 | 2.84 | -1.6% | 4.5% |
| All Units | $564.61 | 7.39 | 4.0% | 12.3% |
| Combined | $600.50 | 4.65 | 0.4% | 7.3% |
Source: SQM Research
National
| Property Type | Rent ($) | Weekly change | Monthly change | 12 Months change |
|---|---|---|---|---|
| All Houses | $786.00 | -7.00 | -0.3% | 5.9% |
| All Units | $618.00 | 4.00 | 1.6% | 7.1% |
| Combined | $708.31 | -1.92 | 0.5% | 6.4% |
Source: SQM Research
Cap City Average
| Property Type | Rent ($) | Weekly change | Monthly change | 12 Months change |
|---|---|---|---|---|
| All Houses | $937.00 | 1.00 | 0.8% | 6.2% |
| All Units | $671.00 | 2.00 | -0.3% | 3.2% |
| Combined | $795.86 | 1.53 | 0.3% | 4.9% |
Source: SQM Research
Here's how many properties are for sale at the moment
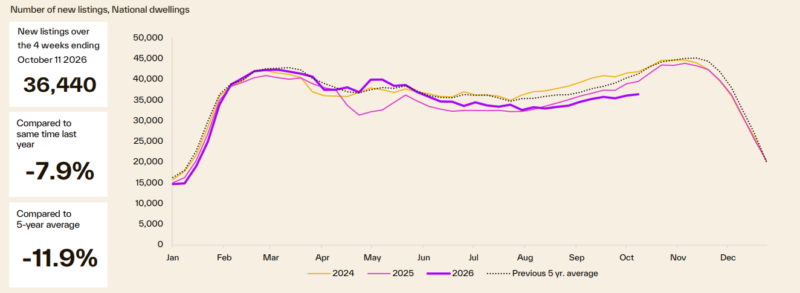
The spring listing season has started slowly.
Over the four weeks ending 11 October 2026, 36,440 new listings came to market, 7.9% fewer than a year earlier and 11.9% below the previous five-year average.
New listings remained close to the five-year average from February to May but have been below it since June and rose only slightly through September, when volumes typically increase
Vendor metrics
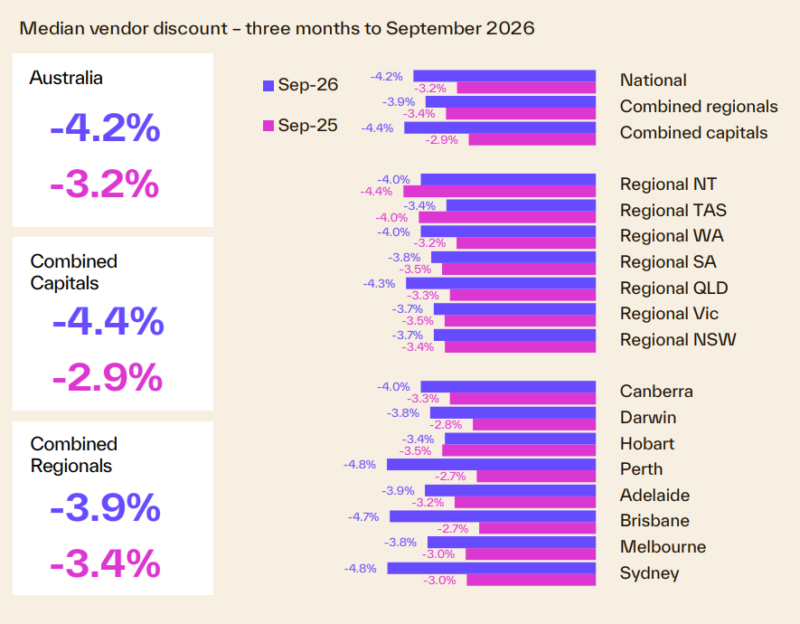
Compared to a year ago, homes are taking slightly longer to sell.
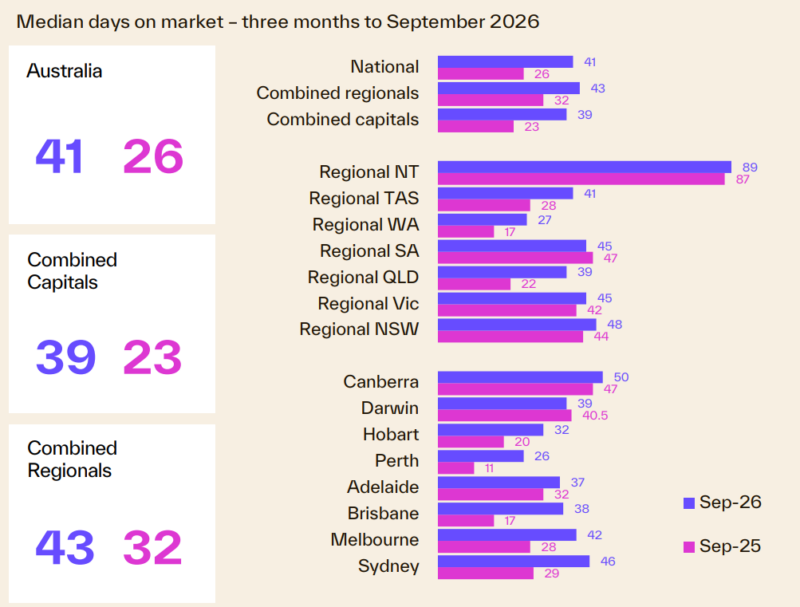
Homes are taking noticeably longer to sell, with the national median time on market extending to 41 days over the three months to September 2026, up from 26 days a year earlier.
The slowdown has been sharpest across the combined capitals, where the median of 39 days is the longest in the five-year series.
Canberra is the slowest-selling capital at 50 days. Perth is the fastest-selling capital at 26 days, though its selling time has more than doubled over the year.
Regional markets have also softened, with selling times lengthening to 43 days from 32, just short of the February 2024 high.