
Key takeaways
Luck plays a bigger role in wealth creation than most people realise. Where and when you're born, your family background and your opportunities can shape your financial future.
Australia remains one of the luckiest countries in the world. Our strong economy, institutions and standard of living provide significant opportunities for building wealth.
Family wealth is increasingly influencing property ownership. Young Australians with financial support from their parents have a significant advantage when entering the housing market.
Education and financial knowledge can help level the playing field. Developing the right skills, habits and mindset can improve your opportunities regardless of your starting position.
Your starting position doesn't have to determine your financial future. Smart decisions, disciplined investing and long-term planning can help you build wealth and create better opportunities for future generations.
What if the most important factor determining your financial future was decided before you were even born?
Before you went to school, chose a career, purchased your first property or made your first investment, the circumstances of your birth had already influenced the opportunities available to you.
It's an uncomfortable thought, particularly for those of us who like to believe our success is largely the result of hard work, intelligence, discipline and good decisions.
And don't get me wrong, I firmly believe those things matter enormously. After more than 50 years of investing, building businesses and helping Australians create wealth, I've seen how the right mindset and financial habits can transform someone's future.
But I've also come to appreciate that we don't all start life's financial journey from the same starting line.
Some people begin with family wealth, excellent education and valuable connections. Others face obstacles that their more fortunate counterparts may never even recognise.
Warren Buffett, one of the world's most successful investors, has a fascinating explanation for this phenomenon.
He calls it the Ovarian Lottery, and understanding it can change the way you think about success, property ownership and the opportunities available to future generations.

For weekly insights, subscribe to the Demographics Decoded podcast, where we will continue to explore these trends and their implications in greater detail.
Subscribe now on your favourite Podcast player:
Warren Buffett's ovarian lottery
Warren Buffett has never been shy about acknowledging the role luck played in his extraordinary success.
He was born in the United States in 1930, into a comfortable, well-connected family, at a time when America's economy and financial markets were about to experience decades of extraordinary expansion.
He was also born male and white, when women and many minority groups faced significant restrictions on their economic opportunities.
Of course, Buffett possessed exceptional investment abilities, worked incredibly hard and demonstrated extraordinary patience and discipline. But he readily acknowledges that those same qualities might have produced very different results had he been born into different circumstances.
As Simon Kuestenmacher explains:
"Before you then add your individual talents, your individual gifts, discipline, and other demographic factors into the mix, so much is already decided."
Simon points out that Buffett's success also coincided with one of the greatest demographic developments of the twentieth century: the emergence of the Baby Boomer generation.
As millions of Baby Boomers moved through adulthood and their peak spending years, they fuelled enormous growth in American consumption and corporate profitability.
Businesses such as Coca-Cola, in which Buffett invested heavily, benefited from this expanding consumer market.
Buffett had the intelligence to recognise opportunities, but the demographic environment helped create those opportunities in the first place.
And that's an important distinction.
Note: Success is usually a combination of ability, effort, circumstances and timing. 
While we can influence some of these factors, others are determined long before we have any say in the matter.
Australia remains one of the luckiest countries in the world
Australians have a habit of complaining about the state of our country, and there's certainly no shortage of things we could improve.
Housing affordability has deteriorated, living costs have increased, and younger Australians are finding it harder to enter the property market.
Yet when we compare Australia with most other countries, we quickly realise how fortunate we are.
We enjoy relatively high incomes, long life expectancy, political stability, strong institutions, widespread access to education and a healthcare system that provides security unavailable to much of the world's population.
Our households also hold considerable wealth, much of it accumulated through homeownership and compulsory superannuation.
Simon puts Australia's position into perspective:
"We remain one of the richest, most fortunate countries on the planet."
He argues that Australians sometimes underestimate just how unusual our circumstances are.
Our natural resources have helped generate enormous national wealth, but the institutions we've developed have also played an important role in maintaining economic opportunity and social stability.
Of course, that doesn't mean everyone shares equally in our prosperity, and it certainly doesn't mean we should accept the shortcomings of our housing or education systems.
However, simply being born in Australia, or having the opportunity to migrate here, provides advantages that billions of people around the world would dearly love to have.
Note: We've already won a significant part of the ovarian lottery simply by living in Australia.
The challenge is ensuring future generations have a reasonable chance of enjoying those same opportunities.
Your postcode can shape your future
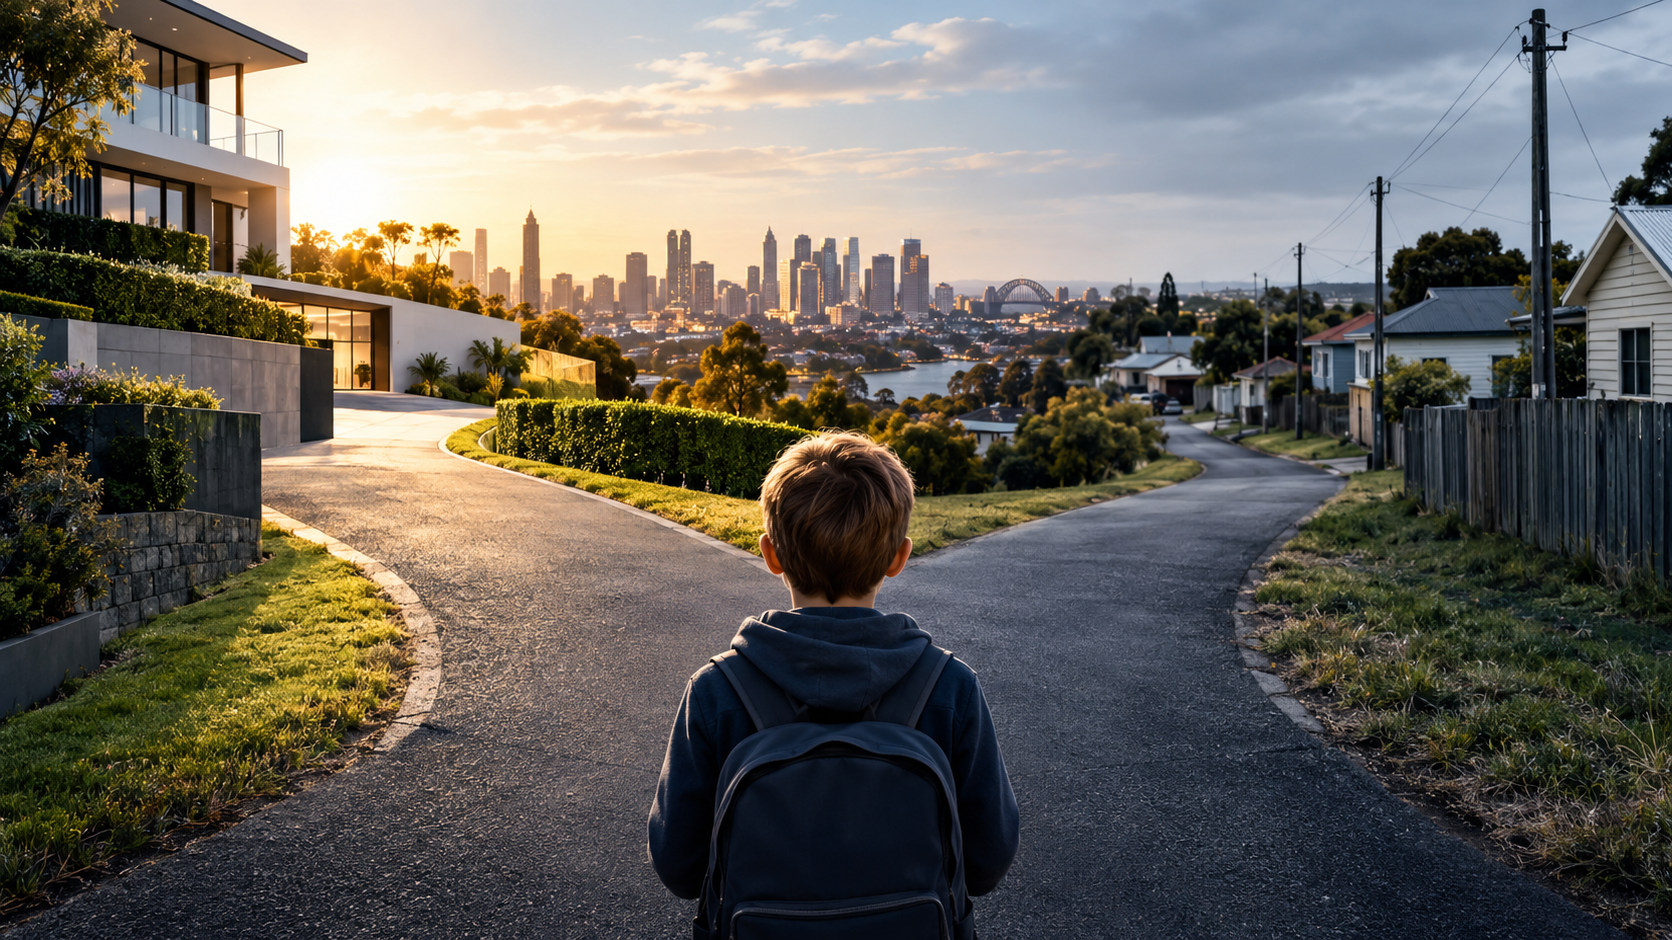
While Australia performs exceptionally well internationally, the ovarian lottery also operates within our own borders.
Consider two children born on the same day in Melbourne.
One grows up in an affluent inner suburb, surrounded by well-educated parents, excellent schools, professional networks and a family that owns valuable property assets.
The other grows up in a financially disadvantaged household, perhaps in an outer suburb or regional community where employment opportunities and educational resources are more limited.
Both children may be equally intelligent, ambitious and hardworking, yet their paths towards financial independence are likely to look very different.
The first may receive help with university expenses, benefit from family connections when seeking employment and eventually receive parental assistance with a home deposit.
The second may need to work while studying, contribute towards household expenses and spend years longer saving for their first property.
Simon explains that these differences are often hidden when we focus on national averages.
"The demographics of your upbringing do matter. And when we just talk about national averages, that of course hides enormous variation."
These disparities extend beyond financial wealth.
Educational outcomes, health, life expectancy and career opportunities can vary considerably depending on where someone grows up, particularly when comparing affluent metropolitan communities with disadvantaged regional and remote areas.
None of this means people from disadvantaged backgrounds cannot achieve extraordinary success. Many do, and their stories are rightly celebrated.
However, exceptional success stories shouldn't distract us from the broader demographic reality that starting with advantages generally makes it easier to accumulate further advantages.
And nowhere is this becoming more obvious than in Australia's housing market.
Property ownership is becoming an increasingly important part of the lottery
For generations, Australians have regarded homeownership as an important step towards financial security.
Owning your home provides stability, reduces exposure to rising rents and allows you to accumulate wealth as property values increase over time.
But homeownership is now playing another role.
It's increasingly influencing the opportunities available to the next generation.
Parents who purchased well-located properties decades ago may have accumulated substantial equity, giving them the ability to help their children enter the housing market.
This assistance might come through a gifted deposit, a family guarantee or an inheritance.
Meanwhile, young Australians whose parents have limited accumulated wealth must often rely entirely on their own savings and borrowing capacity.
Simon makes an interesting observation about the so-called Bank of Mum and Dad.
"The bank of mum and dad, of course, isn't really a bank because a bank actually wants their loan back."
While some families provide genuine loans, much of this assistance effectively reduces the financial burden of purchasing a home.
And as property prices have increased relative to incomes over the long term, family assistance has become an increasingly valuable advantage.
I've often explained that property investment is a game of finance with some houses thrown in the middle.
The ability to access capital, manage debt and use equity strategically can make an enormous difference to an investor's long-term results.
But it's becoming increasingly apparent that access to family capital is also influencing who gets onto the property ladder in the first place.
We naturally want parents to be able to help their children, and I firmly believe families should take a long-term approach to building and passing on wealth.
However, we also need to recognise that talented, hardworking young Australians without wealthy parents face a more difficult journey towards homeownership.
Over time, this could create a society in which family wealth becomes an increasingly important predictor of future property ownership.
Education provides another head start
Education remains one of the strongest influences on future earning capacity, career opportunities and financial independence.
However, educational advantages often begin well before a child enters a classroom.
Families with greater resources can afford desirable school catchments, additional tutoring, educational technology and experiences that broaden their children's understanding of the world.
Simon points to the 2025 NAPLAN results, which continued to show a relationship between socioeconomic advantage and educational outcomes.
- Also read:This week’s Australian Property Market Update – Latest Data, State by State October 27th 2026
- Also read:Latest Property Price Forecasts. Australian Property Market Outlook 2026-2027: Navigating a Market Correction

- Also read:Brisbane Property Market Forecast [2026 & Beyond] – What The Olympics Decade Means for Investors.
- Also read:Melbourne property market forecast for 2026 & 2027 | Separating the fundamentals from the sentiment
- Also read:Sydney property market forecast for 2026 and 2027 | Why the short-term softness is a long-term opportunity
As he explains:
"Education remains the best indicator for your future income."
The concern is that educational inequality can reinforce financial inequality across generations.
Children who receive stronger educational support are generally better positioned to pursue higher-paying careers, accumulate assets and eventually provide similar advantages to their own children.
Of course, education involves much more than formal qualifications.
In my experience, financial education is equally important.
Understanding how money works, why assets matter, how debt can be used responsibly and why delayed gratification is essential to wealth creation can provide an enormous advantage.
Unfortunately, these lessons aren't consistently taught in our schools, meaning many Australians learn them through their families, mentors or personal experience.
Note: That's why I've always believed that one of the greatest gifts parents can give their children is a sound financial education.
Will artificial intelligence make the lottery fairer?
One of the more interesting questions facing future generations is whether technology, particularly artificial intelligence, will reduce the advantages associated with family wealth and location.
A talented teenager growing up in a regional town can now access educational resources, online courses and sophisticated technology that previous generations could scarcely have imagined.
In theory, AI could make high-quality learning and professional knowledge available to people regardless of their financial background.
But Simon warns that technology has historically worked in two directions.
While innovations such as the printing press, internet and smartphone have expanded access to information, those who already possess capital have often been best positioned to benefit financially.
The same may prove true of artificial intelligence.
Companies owning the platforms, computing infrastructure and intellectual property could capture a disproportionate share of the economic rewards.
AI could become a powerful tool for increasing economic mobility, or it could reinforce existing concentrations of wealth.
My view is that individuals who learn to use these technologies effectively will give themselves an advantage, particularly when they combine those skills with financial discipline and a willingness to keep learning.
However, access to technology alone won't eliminate the influence of family circumstances and accumulated wealth.
Gender is another part of the equation
Buffett's original explanation of the ovarian lottery also recognised the advantages he enjoyed by being born male in the United States during the 1930s.
Fortunately, Australian society has changed considerably since then.
Women now outperform men across many educational measures and represent a larger proportion of university graduates.
Nevertheless, career interruptions associated with raising children, differences in occupational choices and caring responsibilities continue to influence lifetime earnings and wealth accumulation.
At the same time, Simon points out that boys and young men are falling behind in several areas of education, creating challenges that deserve greater attention.
Interestingly, I've also observed differences in how men and women approach property investment.
In my experience, many female investors demonstrate considerable patience, undertake thorough research and are more willing to seek professional advice before making significant financial commitments.
Note: These are valuable qualities in property investment, where long-term discipline and risk management often matter more than attempting to identify the next hotspot.
The broader lesson is that gender continues to influence financial outcomes, although the patterns are becoming more complex.
Australia's safety net helps, but housing remains a weakness
One reason Australia continues to offer relatively strong opportunities is that we've developed systems designed to reduce some of the disadvantages associated with the ovarian lottery.
Medicare provides broad access to healthcare, compulsory superannuation encourages retirement savings, and our welfare system offers support to households experiencing financial hardship.
These arrangements don't eliminate inequality, but they help reduce the consequences of being born into less fortunate circumstances.
However, Simon identifies housing as an area where Australia's social and economic arrangements are becoming increasingly strained.
In particular, he raises concerns about Australians entering retirement without owning their homes.
Someone who retires mortgage-free has a very different financial outlook from someone who must continue paying market rents for another 20 or 30 years.
Even with superannuation and government support, ongoing housing expenses can place considerable pressure on retirement incomes.
And as Australia's population ages, the distinction between homeowners and long-term renters could become an increasingly important source of financial inequality.
This reinforces something I've been explaining to property investors for decades.
Note: The financial decisions you make during your working life can have an enormous influence on the choices available to you in retirement.
While property investment isn't suitable for everyone, developing a long-term strategy for accumulating assets and reducing dependence on employment income remains one of the most practical ways to improve financial security.
The ovarian lottery is changing for future generations
When we look at the world over several decades, there's actually plenty of reason for optimism.
Extreme poverty has declined dramatically over the long term, access to education and healthcare has improved, and technological progress has created opportunities previous generations could never have imagined.
Simon points out that, from a global perspective, being born today generally provides better prospects than being born a century ago.
However, within many developed countries, including Australia, differences in accumulated wealth are becoming increasingly influential.
Property ownership, family financial assistance, education and access to technology are all shaping the prospects of younger generations.
Climate change may also influence future opportunities, as households in areas exposed to greater environmental risks face additional challenges.
For Australians who already own substantial assets, these developments create both opportunities and responsibilities.
We have an opportunity to manage our wealth wisely, provide appropriate assistance to the next generation and help our families build long-term financial security.
But a healthy society also needs pathways for capable, hardworking people to succeed regardless of their family background.
Otherwise, inherited advantages risk becoming more important than individual effort and ability.
What does all this mean for your financial future?
After more than five decades of investing, I've become convinced that successful wealth creation involves understanding both the opportunities available to you and the factors within your control.
You can't change where you were born, the family you grew up in or the economic conditions that shaped your early years.
And you certainly can't go back and purchase property at the prices your parents or grandparents enjoyed.
But you can improve your financial knowledge, develop better habits, surround yourself with the right people and make more informed decisions about your future.
You can also recognise the demographic trends shaping Australia's economy, housing markets and employment opportunities, then position yourself to benefit over the long term.
For property investors, that means looking beyond short-term market movements and understanding the forces that create sustained demand for well-located, investment-grade properties.
It also means having a clear strategy, maintaining financial buffers and recognising that patience and discipline remain valuable advantages regardless of economic conditions.
And for those who have already accumulated wealth, there's another opportunity worth considering.
Rather than simply leaving an inheritance after you're gone, thoughtful financial assistance and education during your lifetime may help your children and grandchildren establish themselves when that support can make the greatest difference.
Naturally, this needs to be balanced against your own retirement security and family circumstances.
But creating intergenerational wealth has always been about more than accumulating assets.
It's also about creating opportunities.
The bottom line
Warren Buffett's ovarian lottery reminds us that luck plays a greater role in our lives than many successful people are comfortable acknowledging.
Some Australians begin their financial journey with considerable advantages, while others must work harder to overcome circumstances they never chose.
Yet I believe recognising these differences should make us more determined to create a better future.
Australia remains one of the most fortunate countries in which to live, with strong institutions, considerable national wealth and opportunities that would have been unimaginable to previous generations.
And while our housing affordability challenges and growing differences in family wealth deserve serious attention, we still have the ability to improve our circumstances through education, sensible financial decisions and long-term planning.
Simon summed up an important part of this discussion when he spoke about the need to appreciate what we have while continuing to strive for more.
I think that's a valuable philosophy for both individuals and our country.
Those of us who have benefited from favourable circumstances should be grateful for the opportunities we've enjoyed and consider how we can help the next generation.
And those still building their financial futures should remember that their starting position doesn't have to determine where they eventually finish.

Tip: You may not have chosen the hand you were dealt, but the way you play that hand still matters enormously.
Ultimately, one of the greatest financial achievements is creating a better starting position for the generations who follow us.
Because while we can't choose the circumstances into which we're born, we can influence the opportunities we leave behind.