
Key takeaways
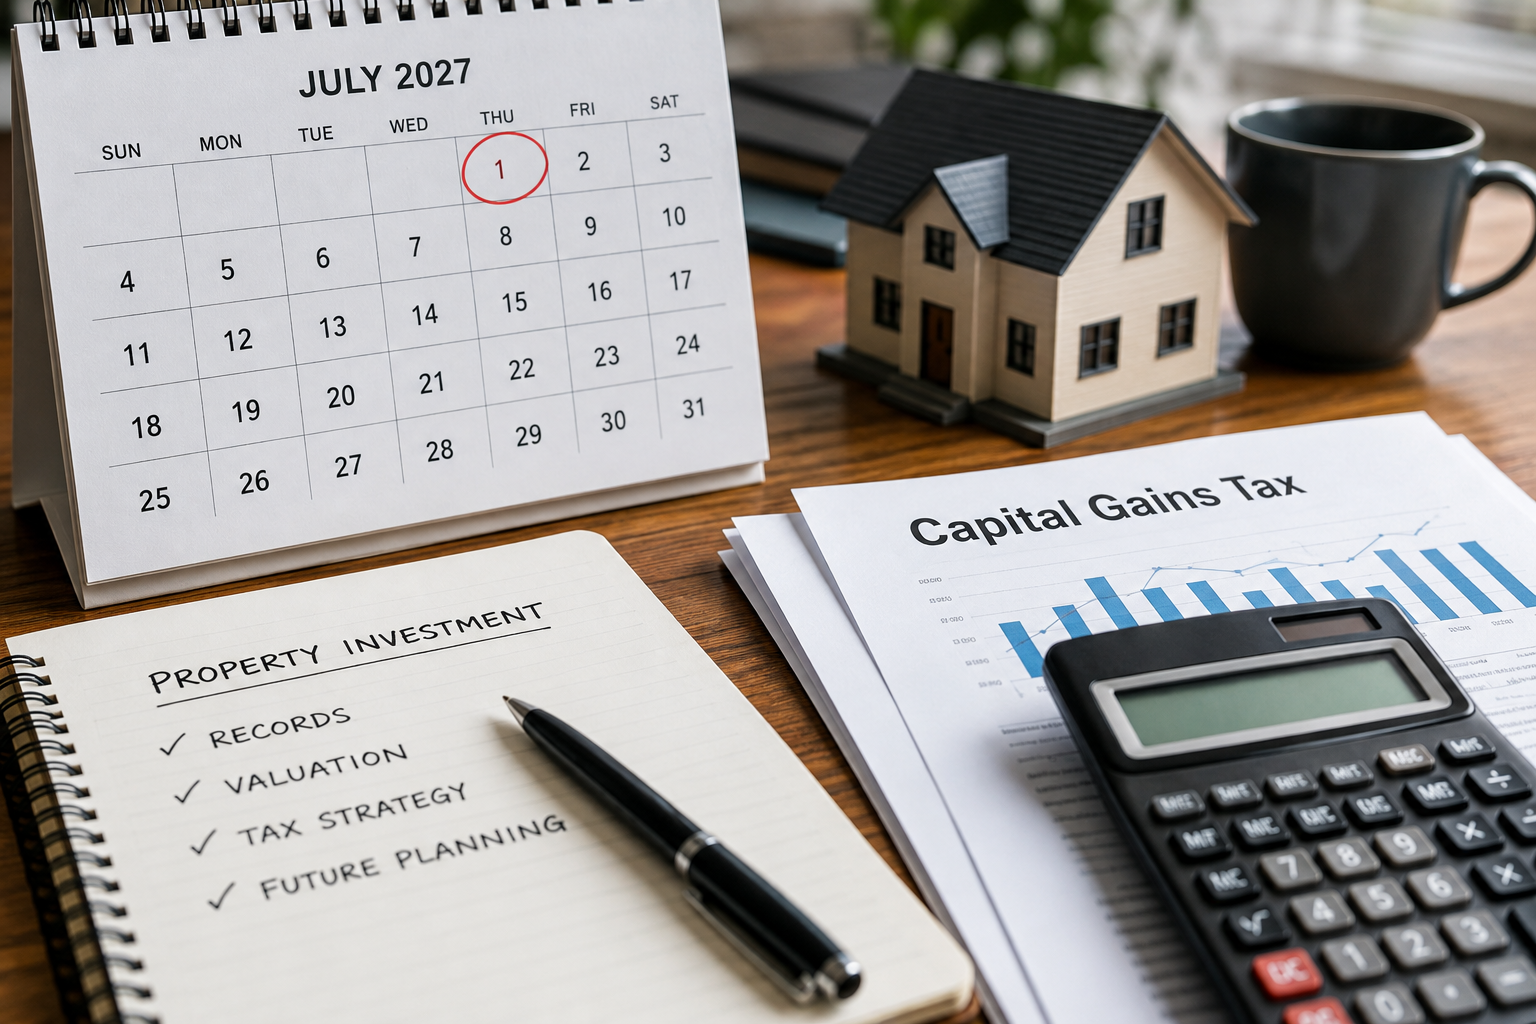
The CGT rules change from 1 July 2027. Gains before and after this date may receive different tax treatment.
Property investors should prepare early. Waiting until you sell could make establishing historical values much harder.
Good records could save you money. Keep purchase costs, renovation expenses, legal fees and other relevant documentation.
Consider getting an independent valuation. Speak with your accountant about whether a valuation around 1 July 2027 makes sense.
Don’t let tax dictate your investment strategy. A quality property with strong long-term growth prospects should remain the priority.
For most property investors, Capital Gains Tax is something they usually think about when they’re preparing to sell.
But the coming changes to Australia’s CGT regime mean there is an important date investors should be thinking about well before their property ever goes on the market.
From 1 July 2027, the current 50% CGT discount for individuals, trusts and partnerships will be replaced by cost-base indexation, together with a minimum 30% tax rate on real capital gains.
Importantly, the new rules are prospective, meaning gains accumulated before 1 July 2027 will continue to be treated under the existing arrangements, while gains accruing after that date will fall under the new system.
That creates a dividing line in the ownership history of the 3 million or so Australian investment properties, and for property investors who plan to hold their assets for many years, getting the numbers right around that date could eventually make a significant difference to their tax bill.
Why 1 July 2027 matters
The challenge is that property prices rarely rise in a neat, predictable fashion.
Anyone who has invested through a few property cycles knows that capital growth tends to occur in bursts. A property might increase substantially over several years, move sideways for a period and then begin another growth cycle.
Different cities, suburbs and even individual properties experience those cycles at different times.
Under the transitional arrangements, investors holding assets across 1 July 2027 will need to distinguish between gains accumulated before and after the changeover.
The rules provide mechanisms for establishing that position, including valuation and prescribed apportionment approaches.
And this is where preparation becomes important.

Tip: If a substantial proportion of your property's growth has already occurred before July 2027, having reliable evidence of its value around the transition date may become extremely valuable when you eventually sell.
Good record keeping could save you money
I've often said successful property investment is a long-term game, and some of our clients at Metropole have owned properties for decades.
- Also read:Migration Is Falling: What Happens to Australian Property Prices Now? | Property Insiders

- Also read:This week’s Australian Property Market Update – Latest Data, State by State September 22nd 2026
- Also read:Latest Property Price Forecasts. Australian Property Market Outlook 2026-2027: Navigating a Market Correction

- Also read:National Weekly Auction Report – September 19th 2026 | Clearance Rates Ease as Auctions Surge

- Also read:Adelaide housing market update | September 2026

Over those sorts of timeframes, paperwork disappears, renovations are forgotten, invoices are misplaced, and memories of what a property looked like at a particular point become increasingly unreliable.
The ATO already expects property owners to retain records relevant to their cost base, including purchase documents, stamp duty, legal and valuation costs and records of eligible capital improvements.
Some ownership costs may also form part of the cost base where they haven't been claimed, or couldn't be claimed, as tax deductions.
With the CGT regime changing, I'd suggest investors start thinking beyond simply keeping a folder of receipts.
Tip: For long-term holders, it may be worth discussing with your accountant or tax adviser whether obtaining an independent valuation around 1 July 2027 would be appropriate for your circumstances.
A valuation prepared close to the relevant date can capture factors that may be much harder to reconstruct years later, including renovations, property condition and local market circumstances.
Don't let tax drive your investment strategy
Of course, there is another side to this discussion.
Investors shouldn't suddenly sell good properties simply because the tax rules are changing. Tax considerations should form part of your investment strategy, but they should rarely be the primary reason for buying or selling an investment-grade asset.
A high-quality property with strong long-term capital growth prospects may still create considerably more wealth after tax than an inferior property purchased primarily because it appears more tax effective.
The smarter response is preparation.
Over the next year, review your portfolio, make sure your property and renovation records are complete, speak with your accountant about how the new rules could affect your circumstances and consider whether valuations will be appropriate as the transition date approaches.
Property investors can't control government policy, tax rules or future property cycles.
What we can control is how well prepared we are for them, and investors who plan ahead will be in a much stronger position to protect the wealth they've worked so hard to build.