
Key takeaways
Every stage of life brings different priorities and opportunities.
Our age influences our financial decisions, housing needs and personal goals.
Life stages can be more revealing than generational labels. Understanding where people are in life helps predict future housing demand and investment trends.
Our approach to wealth creation changes as we age. Younger adults focus on building assets, while older generations increasingly prioritise financial security and passing on wealth.
Australia's ageing population will reshape the property market. Demand for suitable housing, downsizing options and intergenerational wealth planning will continue to grow.
Successful wealth creation is about more than accumulating assets. Financial independence should provide security, freedom and opportunities to help future generations.
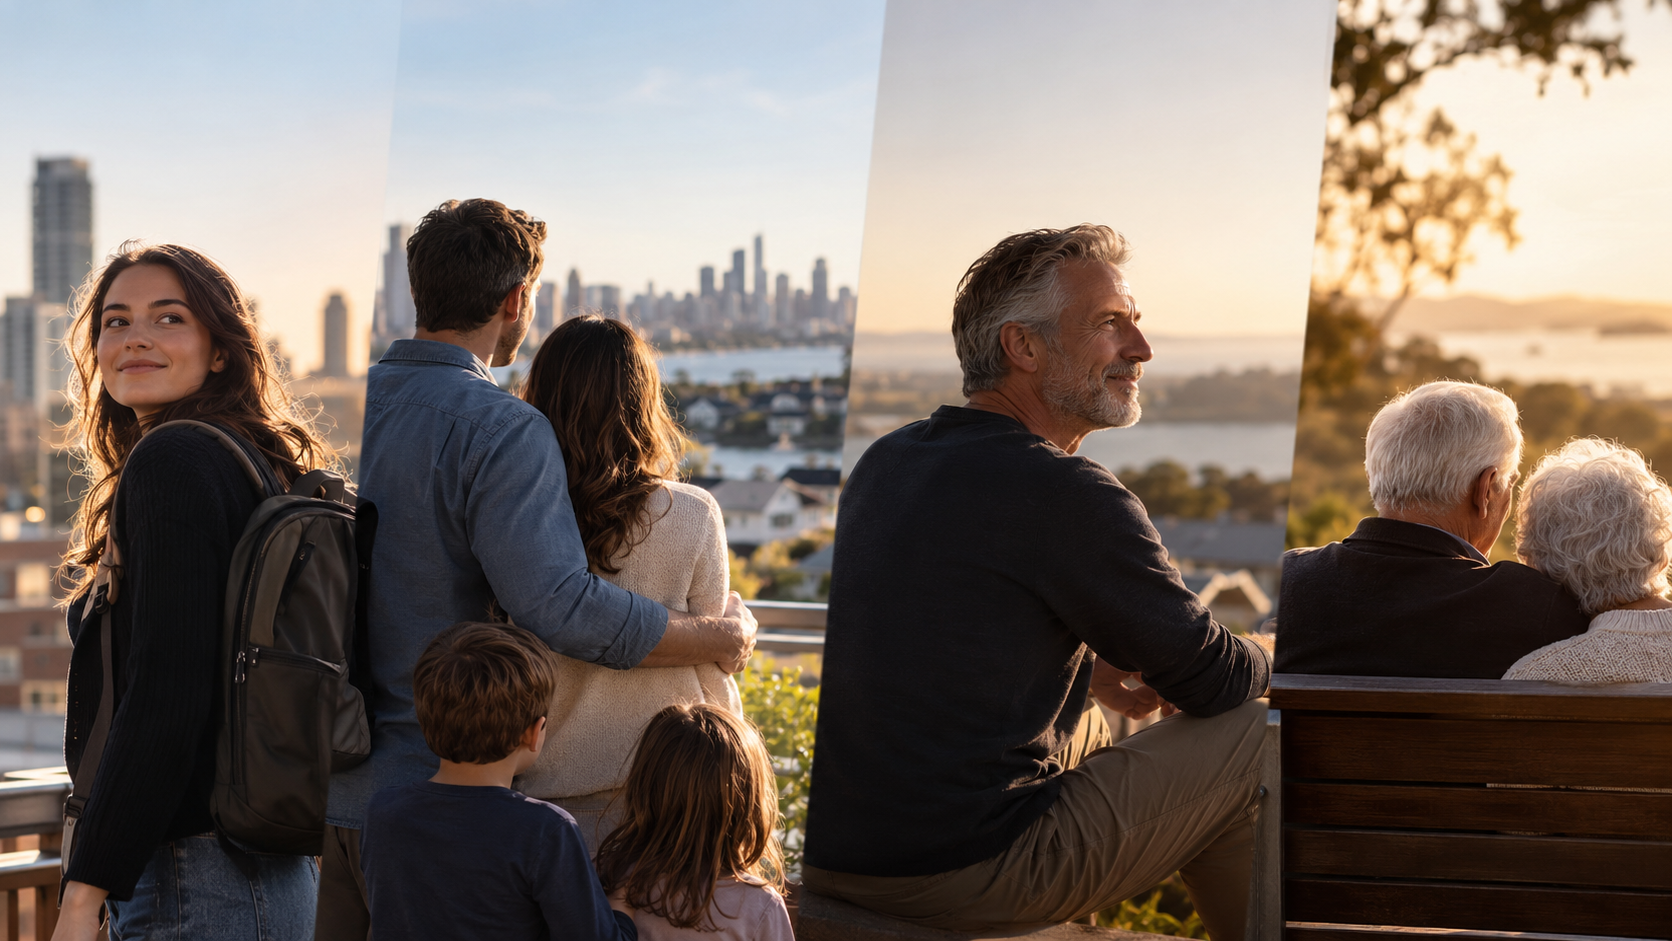
You may have noticed how the things that seemed desperately important to you at 25 barely register when you're 50, while the things you value at 70 might never have crossed your mind when you were younger?
At 25, you might be focused on establishing your career, travelling or saving for your first home.
By 40, your priorities may have shifted towards raising a family and building financial security.
And by 65, you may find yourself thinking more about your health, your grandchildren and what all those years of hard work have actually been for.
Of course, we all age at the same rate, but we certainly don't experience life in the same way.
According to leading demographer Simon Kuestenmacher, understanding these changing priorities can tell us an enormous amount about where Australia is heading, what types of homes people will need and how we should approach our own wealth creation.
There's a fascinating framework developed by educator Thomas Armstrong that divides the human journey into 12 stages, beginning before birth and continuing through to the end of life.
What makes this framework interesting is that Armstrong suggests every stage comes with its own unique gift, something we can learn, develop and carry into the next chapter of our lives.
As Simon explains:
"Age, for me, isn't just a number. It is a strong predictor for human behaviour."
And when you think about it, that makes sense.
Knowing Australia's population will grow by another million people tells us relatively little about what those people will need.
But understanding whether they're young adults establishing households, families looking for more space or older Australians approaching retirement tells us a great deal about future demand for housing, healthcare and other services.
It also helps explain why our priorities, ambitions and financial decisions change as we move through life.

For weekly insights, subscribe to the Demographics Decoded podcast, where we will continue to explore these trends and their implications in greater detail.
Subscribe now on your favourite Podcast player:
Why your stage of life matters more than your generation
We constantly hear about the differences between Baby Boomers, Generation X, Millennials and Generation Z, and while these labels are useful, they can lead to misleading assumptions.
We're told Millennials prefer apartments, Baby Boomers want to downsize and younger Australians are less interested in homeownership.
But every generation moves through broadly similar stages of life, although the circumstances surrounding those stages can be very different.
A 30-year-old today may face higher housing costs and spend longer establishing a career than someone of the same age did 40 years ago.
However, both are likely to be working through similar questions about independence, relationships and financial security.
Simon explains that generations bring their own experiences and values into each stage, shaped by the political, technological and social environment in which they grew up.
This means the way Millennials experience middle age will probably look quite different from the way Baby Boomers experienced it, even though the underlying transitions remain familiar.

Note: For property investors, this distinction matters because people's housing needs are often influenced more by their stage of life, financial position and family responsibilities than by the generation they belong to.
Early adulthood: The gift of enterprise (20 to 35 years)
Armstrong describes early adulthood as the stage of enterprise, when we establish our independence and begin building the foundations of adult life.
Traditionally, this meant completing our education, finding a job, getting married, buying a home and starting a family, often in relatively quick succession.
But today's young Australians are following a different timetable.
They're studying for longer, entering stable employment later, delaying marriage and parenthood, and taking longer to purchase their first home.
Some of this reflects financial pressures, particularly high housing costs and less secure employment. However, it also reflects changing attitudes towards careers, relationships and what constitutes a successful life.
As Simon explains:
"Their enterprise might just be expressed through career experimentation, by reinventing how we work, by reinventing what a career means."
Young adults are increasingly experimenting with different careers, travelling before settling down, pursuing additional qualifications and exploring entrepreneurial opportunities.
It's easy for older generations to interpret delayed homeownership or family formation as a lack of ambition, when younger Australians may simply be expressing that ambition differently.
From a demographic perspective, these changes have significant implications for our housing markets.
When people delay marriage and children, they spend longer living in smaller households, often renting apartments or other relatively affordable accommodation close to employment and lifestyle opportunities.
Note: For property investors, understanding how long people remain in this stage, and what accommodation they'll need, provides valuable clues about future rental demand.
Midlife: The gift of contemplation (35 to 50 years)
After years of establishing careers, building relationships, raising children and pursuing financial goals, something interesting often happens.
We begin to question whether the life we've worked so hard to create delivers what we expected.
Armstrong calls this the gift of contemplation, and I suspect many readers will recognise the feeling.
Perhaps you've reached a point in your career where you're financially comfortable but no longer excited by another promotion.
Maybe you've built a successful business but are questioning whether the long hours are worth it. Or perhaps you're beginning to think seriously about what financial independence might look like.
As Simon explains:
"You step back, you take stock, you reconsider your priorities."
While this stage has traditionally been associated with the so-called midlife crisis, contemplation can be constructive when it encourages us to reassess our priorities and make more deliberate decisions.
And it's particularly relevant to property investment.
At Metropole, we often find that people in this stage begin thinking seriously about their financial future.
They've built equity in their family homes, established careers and accumulated reasonable incomes, but they're recognising that earning a good salary doesn't necessarily guarantee financial freedom.
They're also becoming aware that their children may need financial assistance to enter the property market, while their own retirement is approaching faster than they once imagined.
Consequently, their investment decisions become more strategic, with greater emphasis on building a portfolio that supports long-term financial independence.
That is why I've always believed property investment should start with a clear strategy. Property is the vehicle, but your financial plan is the driver, and that plan needs to evolve as your circumstances change.
Interestingly, Millennials, Australia's largest generational cohort, will increasingly occupy this stage over the coming decade.
Their decisions about families, housing, careers and wealth creation will have significant consequences for our economy and property markets.
Mature adulthood: The gift of benevolence (50 to 80 years)
As we move into mature adulthood, our priorities often begin shifting beyond our own achievements and financial security towards the wellbeing of others.
Armstrong calls this the gift of benevolence.
It's the stage when many people become increasingly interested in mentoring younger colleagues, supporting their communities, volunteering, helping their children financially and spending time with grandchildren.
Simon makes the interesting observation that much of this contribution is economically invisible.
Grandparents providing childcare, retirees volunteering and experienced professionals mentoring younger people don't necessarily add directly to measured economic output, yet these activities provide enormous value to families and communities.
And there's another dimension particularly relevant to Australia's future.
We're entering a period when substantial amounts of wealth accumulated by older generations will eventually pass to their children and grandchildren, although many families are already transferring some of that wealth while the older generation is still alive.
The Bank of Mum and Dad has become an increasingly important source of assistance for younger Australians struggling to enter the housing market.
As Simon points out, helping children reduce their mortgage can produce benefits far greater than the original contribution because it also reduces the interest they'll pay over the life of the loan.
Of course, providing financial assistance requires careful planning. Parents need to protect their own retirement security, consider other family members and understand the legal and financial implications.
But the broader principle is important.

Tip: Successful wealth creation increasingly involves thinking beyond the individual investor and considering how financial decisions can benefit the entire family over several generations.
I've noticed this shift among experienced property investors who initially focused on building their own financial independence but eventually became more interested in protecting and passing on their wealth.
- Also read:This week’s Australian Property Market Update – Latest Data, State by State October 20th 2026
- Also read:Latest Property Price Forecasts. Australian Property Market Outlook 2026-2027: Navigating a Market Correction

- Also read:Brisbane Property Market Forecast [2026 & Beyond] – What The Olympics Decade Means for Investors.
- Also read:Melbourne property market forecast for 2026 & 2027 | Separating the fundamentals from the sentiment
- Also read:Sydney property market forecast for 2026 and 2027 | Why the short-term softness is a long-term opportunity
And the knowledge, values and financial habits we pass on can be just as valuable as the assets themselves.
Late adulthood: The gift of wisdom (80 years and beyond)
Australia's population is ageing, and Simon points out that people aged over 80 represent one of our fastest-growing age groups in relative terms.
Much of the discussion surrounding this demographic trend focuses on healthcare costs, aged care services, pensions and workforce shortages.
These are legitimate concerns, but Armstrong's framework encourages us to recognise something else.
Older Australians possess an enormous reservoir of experience and perspective that younger generations would be foolish to ignore.
Simon describes them as the custodians of memory, people who have witnessed economic crises, technological revolutions, political upheavals and changing social attitudes over many decades.
As he puts it:
"Wisdom can't be just downloaded by a young person. This has to be accumulated over time."
I can certainly relate to that. Having spent more than five decades involved in property investment, I've lived through numerous economic cycles and heard countless predictions about the imminent collapse of Australia's housing markets.
Some downturns were painful, and I know some investors suffered significant losses, but experience has taught me the importance of maintaining perspective and understanding the forces shaping long-term property values.
Younger investors today face a constant stream of headlines, social media commentary and conflicting forecasts, which can make every market movement feel unprecedented.
Tip: One advantage of experience is the perspective to recognise that uncertainty has always been part of investing.
However, wisdom becomes particularly valuable when it's shared.
Families should begin discussing issues such as housing preferences, downsizing, aged care, estate planning and financial arrangements well before an elderly parent experiences a health crisis.
We also need to recognise that older Australians often have strong emotional attachments to their homes and communities.
A family home represents decades of memories and relationships, which helps explain why many older Australians are reluctant to downsize even when a smaller property might appear more practical.
Understanding these motivations matters for families, policymakers and property investors alike.
The final stage: The gift of life
Perhaps the most confronting part of Armstrong's framework is the final stage, associated with death and dying.
He describes its gift as life itself.
The underlying idea is that recognising our time is limited helps us appreciate what matters most.
Simon has an interesting personal practice of reminding himself that he will eventually die and that his children will one day grow old. He says this awareness influences how he allocates his time between work, family and other commitments.
While contemplating our mortality isn't particularly comfortable, there's considerable value in recognising that financial success is only one part of a fulfilling life.
After all, building a substantial property portfolio means relatively little if we never enjoy the freedom, security or opportunities that wealth was supposed to provide.
Note: It's also why estate planning, succession arrangements and conversations about family wealth shouldn't be left until the final years of life.
The earlier we clarify our intentions, the more opportunity we have to make thoughtful decisions and prepare the next generation.
Another way of looking at life: Building your container
Simon also introduced another interesting framework developed by Franciscan priest and author Richard Rohr, who divides life into two broad halves.
In the first half, we're primarily concerned with building what he calls our container.
We establish our identity, develop careers, create relationships, raise families, accumulate assets and work towards financial security.
The second half involves examining what we've built and considering its deeper purpose.
We become more interested in wisdom, compassion, contribution and understanding what gives our lives meaning.
Importantly, this transition isn't necessarily determined by chronological age. Some people begin asking these questions relatively early, while others remain focused on achievement and accumulation throughout their lives.
I find this framework relevant to wealth creation because it highlights something I've observed among successful investors.
Initially, many people are motivated by financial goals such as owning several properties, achieving a particular net worth or replacing their employment income.
But as they progress, their definition of success often changes.
Financial independence becomes valuable because of the choices it provides, the security it offers their families and the opportunities it creates to contribute to others.
The purpose behind wealth creation becomes increasingly important as we move through life.
What these life stages mean for property investors
While Armstrong's framework is primarily concerned with personal development, it offers valuable lessons for anyone making long-term investment decisions.
Our housing needs and financial priorities change throughout life, which means a property investment strategy that made sense at 30 may need significant adjustments by 50 or 65.
During the enterprise stage, the emphasis may be on establishing financial foundations and making the first investments.
As we enter contemplation, we may focus more on building a portfolio that provides financial independence while balancing family responsibilities.
During mature adulthood, priorities often shift towards protecting accumulated wealth, preparing for retirement and helping children or grandchildren.
Later in life, decisions about income, estate planning, housing arrangements and passing on wealth become increasingly important.
These same transitions also influence property demand across Australia.
As younger adults delay family formation, demand for rental accommodation and smaller households may remain stronger for longer.
When large generations move into their family-formation years, demand can shift towards established suburbs offering larger homes, schools, transport and family-friendly amenities.
And as Australia's older population grows, we'll need more accessible housing, suitable downsizing options and accommodation that allows people to remain connected to their communities.
Of course, demographics alone don't determine property prices. Affordability, employment, housing supply and local market conditions also play important roles.
But demographic trends provide an essential foundation for understanding where demand is likely to emerge over the longer term.
And because property investment is a long-term undertaking, these changes deserve considerably more attention than the latest monthly price movements.
Making the most of the stage you're in
One of the things I particularly liked about Simon's interpretation of Armstrong's framework is that he cautions against treating the stages as rigid categories.
People develop at different rates, experience different circumstances and sometimes revisit earlier priorities as their lives change.
The value of the framework lies in using it as a checkpoint, encouraging us to reflect on where we are and whether we're making the most of the opportunities available.
Simon mentioned experienced property investors who have accumulated enough wealth for their own needs and are now using their properties to help people facing difficult circumstances.
Some are providing accommodation to single parents or people escaping domestic violence, sometimes at significantly reduced rents.
It's a wonderful example of the benevolence Armstrong describes.
As Simon explains:
"The ultimate goal is to introduce more people into your circle of compassion."
I think that's a valuable perspective for all of us, regardless of our age or financial circumstances.
I've long believed successful property investment requires patience, discipline, a sound strategy and the ability to look beyond short-term market fluctuations.
But ultimately, the purpose of creating wealth is to improve the quality of our lives and provide opportunities for the people who matter to us.
Armstrong's framework reminds us that our priorities will continue evolving as we grow older, and that each stage offers opportunities to learn, contribute and prepare for what comes next.
So wherever you find yourself on life's journey, I'd encourage you to consider whether your financial plans and personal priorities still reflect the person you've become and the future you want to create.
After all, ageing is inevitable, but growing wiser, becoming more financially secure and making a positive contribution to the people around us are opportunities we can choose to embrace.
And perhaps that's the most encouraging lesson of all. The best years of your life don't necessarily have to be behind you, because each new stage can bring its own opportunities, rewards and reasons to look forward to the future.