Key takeaways
National dwelling approvals fell 2.7% in July after rising 6.7% in June.
Detached house approvals declined 4.2%, while the more volatile unit sector fell 0.4%.
Approvals remain 23.4% below their 2016 capital-city peak, despite Australia’s growing housing shortage.
Unit approvals are 40.8% below their 2016 peak.
House-building costs are now 4.2% higher than a year ago and approximately 66.5% above January 2018 levels.
Brisbane recorded the strongest year-to-date increase in total approvals, while Sydney and Melbourne remained weaker.
Auction clearance rates improved in most capitals over the weekend, although Sydney moved backwards.
The growing gap between housing demand and the industry’s ability to deliver new homes should support the value of established, investment-grade property over the long term.
Australia desperately needs more homes, yet the latest building approval figures show how difficult it will be to deliver them.
National dwelling approvals fell 2.7% in July, with approvals for detached houses dropping 4.2% and units declining 0.4%.
At the same time, the cost of building a new home is rising again, placing further pressure on builders, developers and buyers.
So, while governments continue to announce ambitious housing targets, the construction industry is sending a very different message. Most new apartment developments are just not financially feasible and won't come out of the ground.
In this week’s Property Insiders, Dr Andrew Wilson and I examine the latest building approval figures, the renewed rise in construction costs and the early signs from the spring auction market.
Taken together, these figures reinforce a theme we have discussed for some time.
Australia’s housing shortage is likely to become more entrenched because the homes we need are becoming more expensive and more difficult to deliver.

Home building approvals fall again in July
Watch this week's Property Insiders show as Dr Andrew Wilson explains that national home building approvals fell 2.7% over July, following a 6.7% rise in June.
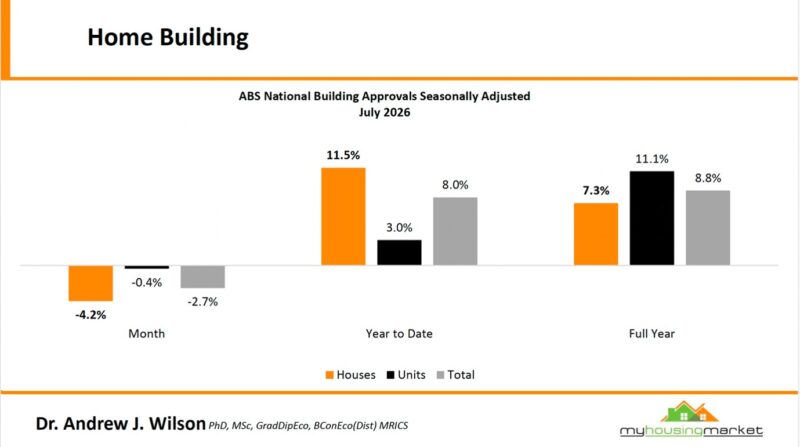
Houses drove most of the monthly weakness, down 4.2%, while the more volatile unit sector eased a smaller 0.4%.
That kind of month to month swing is fairly normal in approvals data, since it is one of the most volatile indicators the Australian Bureau of Statistics publishes mainly because approvals for large apartment complexes can create large swings in the data.
What matters more is the underlying trend, and on that measure the picture is a little more encouraging than the monthly headline suggests.
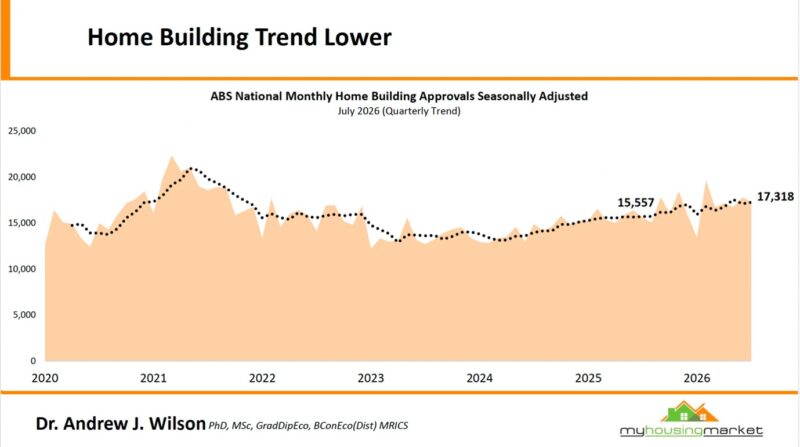
The quarterly trend for national approvals has actually been climbing, moving from 15,557 to 17,318 over the past year.
Houses on trend have lifted from 9,620 to 10,199, and units have moved from 5,937 to 7,119.
So while the monthly number looks like a step backwards, the broader direction of travel is still gradually improving, even if it remains well short of where the market needs to be.
Victoria bucks the national trend
The standout figure in this month's data belongs to Victoria, where total home approvals rose 9.7% for the month.
That puts Victoria well out in front of every other state, at a time when most of the country is either flat or going backwards.
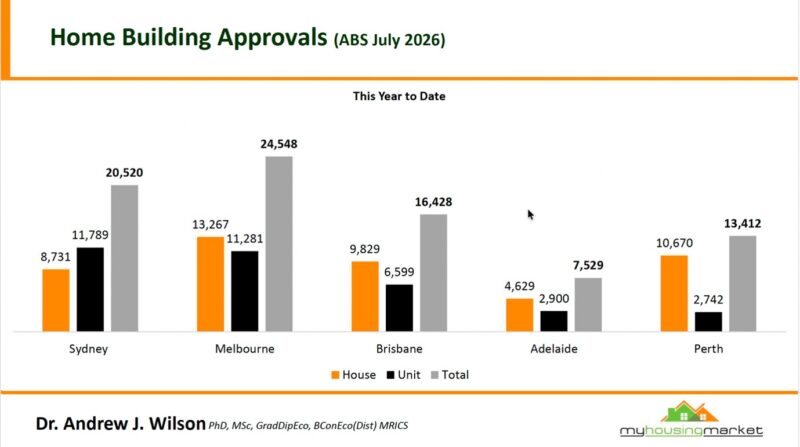
Looking at the year to date numbers by capital city tells an even more interesting story.
Melbourne has approved 24,548 total homes so far this year, ahead of Sydney's 20,520, Brisbane's 16,428, Perth's 13,412 and Adelaide's 7,529.
On a year on year basis, Brisbane has recorded the strongest growth, up 40.1% for total approvals, driven by a remarkable 62.3% surge in unit approvals.
Perth is up 16% for the year, Adelaide is up 4.3%, and Sydney has actually gone backwards 1.8% for total approvals, weighed down by a 13.3% fall in unit approvals.
Melbourne sits close to flat, down 3.8% for the year to date, but that follows several years of Victoria leading the nation on new supply, so a period of consolidation isn't unexpected.
For long-term investors, this data reinforces something I've said for years, which is that Australia doesn't have one property market.
It has eight, and right now the construction cycle in each of them is moving at a genuinely different pace.
Capital city approvals still well below their 2016 peak
Zoom out to the longer-term picture and the scale of the supply problem becomes even clearer.
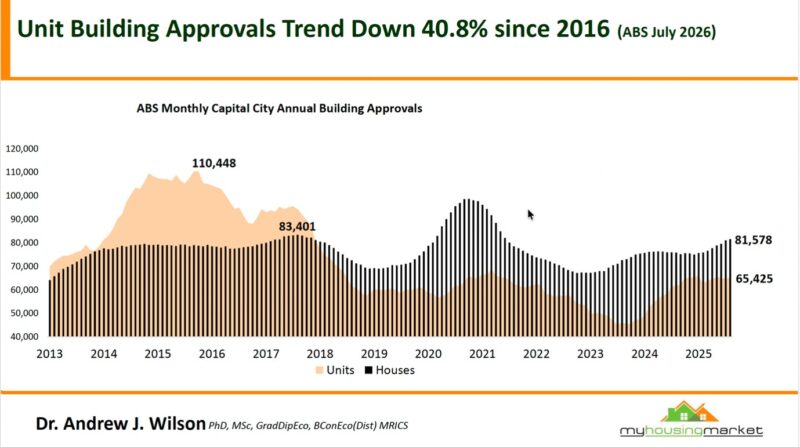
Annual capital city dwelling approvals peaked at 189,409 back in 2016 and now sit at 147,003, a fall of 23.4% from that high.
The unit sector has been hit even harder, with capital city unit approvals down 40.8% since their 2016 peak of 110,448, now sitting at 65,425.
This is the story that sits underneath every rental crisis headline you've read over the past few years. Australia has been building fewer homes, particularly fewer units, at exactly the time population growth has been running hard.
That mismatch doesn't resolve itself quickly, and these figures confirm it is still very much in play.
Building costs keep climbing
Watch this week's Property Insiders show as Dr Andrew Wilson breaks down why house building costs rose again over July.
- Also read:Sydney housing market update | September 2026

- Also read:The Housing Number That Makes No Sense Right Now | Property Insiders

- Also read:Melbourne housing market update | September 2026

- Also read:This week’s Australian Property Market Update – Latest Data, State by State September 15th 2026
- Also read:Australian housing market update | September 2026

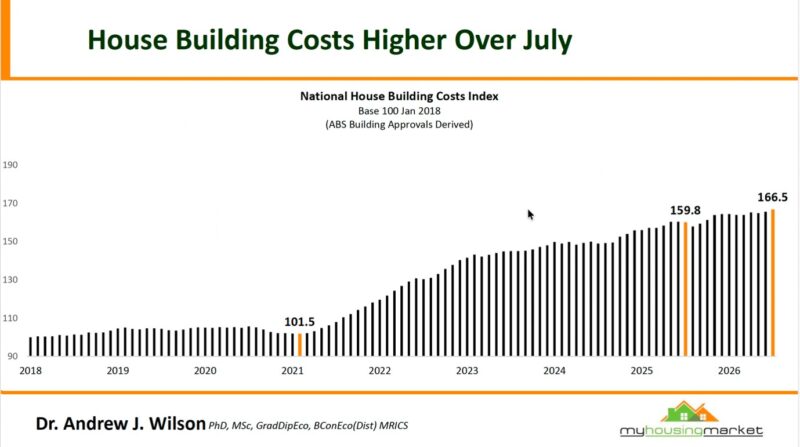
The national house building costs index, based on ABS building approvals data, now sits at 166.5, up from a base of 100 back in January 2018.
That means it now costs roughly two thirds more to build the average house than it did less than eight years ago.
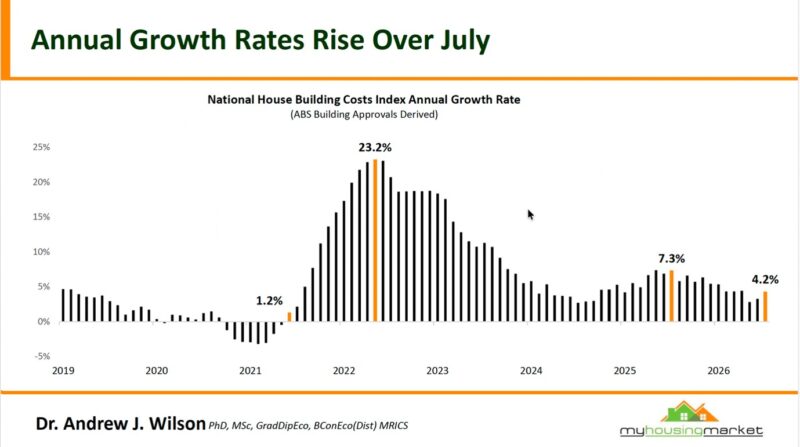
Annual growth in building costs accelerated to 4.2% in July, up from a low of just 1.2% in mid 2021, before the post-pandemic construction cost blowout took hold.
At its peak in 2022, annual cost growth hit an extraordinary 23.2%, driven by material shortages, labour constraints and supply chain chaos that followed the pandemic.
Growth has eased considerably since then, but the fact it's accelerating again from 1.2% is worth watching closely.
Higher building costs discourage developers from bringing new supply to market, particularly in the unit sector where margins are already tight.
That creates a difficult feedback loop, where the very costs that make new housing more expensive to build are also part of the reason we aren't building enough of it.
Housing targets remain increasingly difficult to achieve
The Federal Government’s National Housing Accord target calls for 1.2 million well-located homes to be constructed over five years.
That requires an average of 240,000 completed homes each year, a level Australia has never sustainably achieved.
Approvals are only the first stage of the process. A dwelling must then be financed, commenced, built and completed, and considerable leakage occurs between each stage.
Some approvals lapse, some projects are redesigned, and others are delayed or abandoned because the developer cannot obtain finance or presales.
Even when construction begins, builder insolvencies, labour shortages and cost overruns can create further delays.
This is why announcing housing targets does not create more housing.
Australia needs a coordinated response that deals with planning restrictions, infrastructure bottlenecks, construction productivity, labour availability, financing constraints and the taxes imposed on new housing.
Unfortunately, many of the policies intended to improve affordability stimulate demand while doing relatively little to increase supply.
Helping more buyers enter the market may be politically attractive, but additional purchasing power chasing an inadequate number of homes eventually feeds into higher prices.
Spring auction markets remain positive for most capitals
There were some early signs of improved auction activity as the spring selling season gathered momentum.
Most capitals reported higher clearance rates from increased or relatively solid listing numbers, although Sydney was the exception.
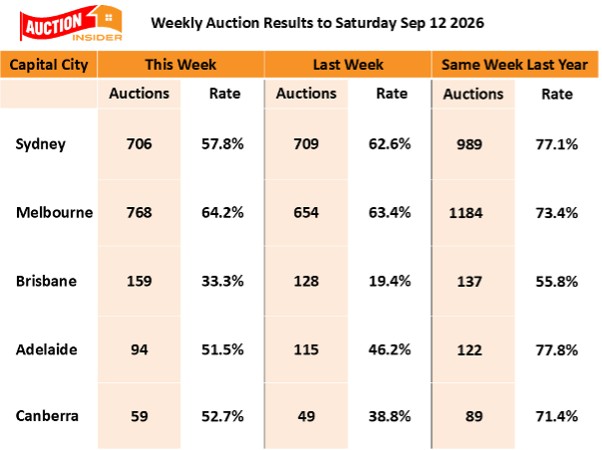
The early spring results suggest buyer demand is still present, particularly for well-located properties priced in line with current conditions.
However, the significant gap between this year’s and last year’s clearance rates confirms that buyers remain cautious and price-sensitive.
What does this mean for property investors?
The latest figures strengthen the long-term case for investment-grade residential property, but they do not mean every property will perform well.
Australia’s population will continue to grow, households will continue to form, and people will continue to want to live near employment, education, transport and lifestyle amenities. Yet the construction industry is struggling to provide enough suitable homes in these locations.
Rising building costs will also make established properties more attractive relative to new stock, particularly where land is scarce, and replacement costs are high.
This creates a significant long-term tailwind for well-located houses, townhouses and family-friendly apartments in our capital cities.
However, investors should remain highly selective because higher construction costs will not rescue an inferior property in the wrong location.
I would continue to favour established properties in affluent inner and middle-ring suburbs where owner-occupiers dominate the market, household incomes are rising, and there is limited capacity to add competing supply.
At this stage of the cycle, investors also need secure finance, substantial cash-flow buffers and a strategic property plan that accounts for changing tax, lending and market conditions.
The housing shortage will take many years to resolve, and the latest approval figures suggest we are continuing to fall behind.
That doesn’t guarantee uninterrupted price growth, but it does provide a powerful foundation for the long-term performance of scarce, desirable property in the locations where Australians want and can afford to live.