
Key takeaways
Know your numbers before investing.
Understanding purchase costs, cash flow, tax implications and borrowing capacity is essential to building a successful property portfolio.
Capital growth should be your priority. Tax benefits and rental income are important, but long-term capital growth is the biggest driver of property wealth.
Negative gearing isn't a substitute for a good investment. Tax deductions can help reduce holding costs, but poor capital growth can leave investors financially worse off.
Always budget conservatively and maintain financial buffers. Allow for unexpected expenses, higher interest rates and periods of weak rental growth to protect your portfolio.
Time and compounding are powerful wealth-building tools. Buying quality assets, using leverage wisely and holding for the long term can significantly increase your wealth.
Thinking of buying a property and not sure of the numbers?
Given the current tax changes and economic environment, buying without understanding the numbers is a gamble.
With negative gearing and capital gains tax both changing, the gap between investors who run the numbers and those who don't is about to get much wider.
That makes it even more important to understand how tax works for property investors, why compounding matters, which hidden costs catch people out, and how to structure your finance so you can keep growing.
There's a great line from Zen teacher Shunryu Suzuki Roshi that I love: "In the beginner's mind there are a few possibilities, but in the expert's there are many."
The best investors retain that open, curious mindset and see more possibilities as a result.
The more you learn, the more opportunities you begin to recognise. Let's look at some of them

Change the order: earn, spend, then pay tax
Most salary earners pay tax first and live on what's left.
Strategic investors flip the order: they spend on legitimate, deductible expenses first, then pay tax on the remainder.
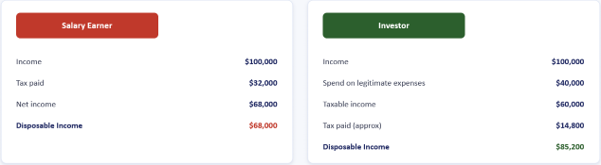
Same income, roughly $17,000 less tax.
And by "legitimate expenses", I mean interest, depreciation, maintenance, property management and similar costs, rather than jet skis or overseas holidays.
A word of caution, though: tax should never be the main reason you buy a property. Too many people start with the tax break rather than the quality of the investment.
Buy the right asset first; the tax benefits become the icing on the cake.
The two taxes every investor pays and why timing changes everything
Every property investor deals with two taxes:
- Income tax on your rental income (just like your salary), less your legitimate deductions.
- Capital gains tax when you sell.
CGT is changing significantly. From 1 July 2027, the 50% CGT discount is being replaced with cost base indexation and a 30% minimum tax rate on real capital gains.
Sell before then and the old rules, including the 50% discount, still apply.
The bigger lesson is that the most successful investors I know rarely sell.
They hold for as long as possible and generally pay CGT only when they eventually sell, allowing more of their capital to keep compounding along the way.
Consider a simple thought experiment: one dollar that doubles every year for 20 years.
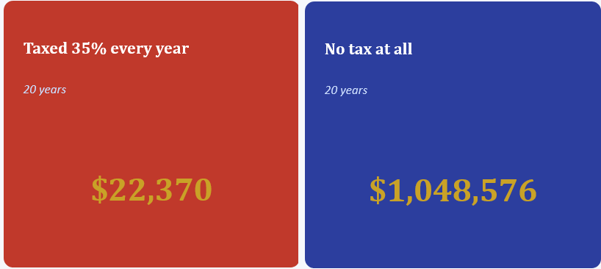
No real asset doubles every year, of course, but the principle holds: deferring tax lets the full amount keep compounding, year after year.
Even after paying 35% at the end, you finish roughly 30 times better off than paying tax every year.
That's how many everyday Australians build multi-million-dollar portfolios: buying well, holding and compounding over decades, rather than years.
Deductions, negative gearing and the traps to avoid
The everyday deductions available to property investors include:
- Interest on your investment loan (not the principal)
- Insurance, agent fees, maintenance and repairs and other running costs
- Depreciation: older buildings have little left to claim, so we usually model it at zero. Newer properties let you depreciate the building and, in the early years, the fixtures and fittings too
- Negative gearing: still available on grandfathered properties, but for established properties bought after the Budget, losses will no longer offset your wages under the new rules
Negative gearing can be a genuine benefit, especially with cost-of-living pressures and higher interest rates. But the strategy relies on the property delivering sufficient growth over time.
If your property only grows at 3–4% a year, as some did between 2010 and 2020, it can cost you more to hold than you may ever get back.
The four traps that turn negative gearing into a money pit:
- Poor capital growth: choose the wrong asset and the maths never works
- Rising interest rates: more increases are likely, so build them into your numbers
- Poor rental growth: buy where rents will keep rising faster than inflation, not just with it
- Lack of financial discipline: never raid your buffer. Taking a couple of thousand out here and there feels harmless until the market shifts, and as the last few years have shown, it can shift fast.
Many investors underestimate what it actually costs to buy a property.
- Also read:Sydney housing market update | October 2026

- Also read:Melbourne housing market update | October 2026

- Also read:Australian housing market update | October 2026

- Also read:Latest Property Price Forecasts. Australian Property Market Outlook 2026-2027: Navigating a Market Correction

- Also read:Brisbane Property Market Forecast [2026 & Beyond] – What The Olympics Decade Means for Investors.
Allow up to around 5% of the purchase price for:
| Cost | What to know |
| Stamp duty | Varies widely by state. Victoria's is higher than most, so model the state you'll actually buy in |
| Land tax | Also varies by state. Don't run your numbers on a Queensland purchase, then buy in Melbourne and get caught out |
| Conveyancing and legal | Skip the bottom-of-the-barrel option. Aim between a mid-range conveyancer and a solicitor: roughly $1,500–$2,500 |
| Finance costs | Applications, valuations and other lender fees; most should be outlined up front |
| Lenders mortgage insurance | Usually applies when borrowing over 80%. On an investment loan it's generally claimable as a borrowing cost; check the treatment with your accountant |
| Inspections and reports | Building and pest, strata reports, and a due diligence report for any development |
Those costs add up quickly, so it pays to get the numbers right before you buy.
Model every deal conservatively and protect your buffer
Before we buy anything, we model it in detail.
Here's how we approach an $850,000 purchase:
- Include every cost: all the purchase costs above, plus a buyer's agent if you use one
- Be conservative on growth: Australian property has averaged a little over 7% a year. We take about 1% off and model established properties at around 6–6.5%, and new properties lower again
- Allow 25–35% of rent for expenses: if your rental expenses come in lower, you've probably missed something, such as land tax or regular maintenance. You might not spend $1,000 each year, but when a $5,000 job arrives in year four or five, it evens out
- Factor in depreciation and tax credits honestly, based on the property you're actually buying
In our example, with 100% borrowing, the property costs roughly $300 a week (about $15,500 a year) to hold after negative gearing and depreciation, which together are worth around $23,000 a year in tax credits.
Now take those benefits away, as will happen for an established property bought after the Budget and the pre-tax holding cost jumps to about $38,500 a year, roughly two and a half times as much.
You can still claim those losses in future, but it could take 7–10 years for the property to reach positive cash flow and trigger your ability to recoup.
It's easy to see how a buffer can be eroded over a few years.
Be wary of anyone projecting 10% capital growth and 10% rental increases every year for 20 years. Those assumptions are far too optimistic.
Where property returns really come from
Property returns come from four sources:
- Capital growth: the big one. Aim for above-average, wealth-producing growth by buying in the right place at the right time
- Cash flow: rental income, ideally where a shortage of properties means rents grow faster than average
- Equity gains you create: property is one of the few assets where you can add value yourself. Paint, renovate, rebuild and lift the rent and claim the depreciation
- Tax benefits: the deductions and deferrals covered above
To compare property fairly against shares or a term deposit, we use the internal rate of return (IRR).
It combines every inflow and outflow (deposit, costs, rent, growth and tax) into one percentage.
Why a lower headline return can win
| Asset A: property | Asset B: shares | |
| Annual growth | 7% | 9% |
| Yield | 4% | 5% |
| Typical borrowing | 80–90% | around 50% |
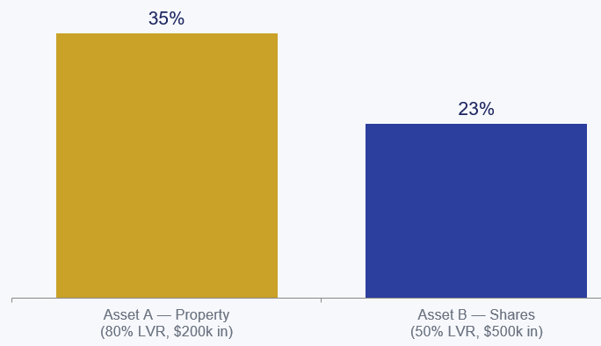
On the headline numbers, Asset B clearly looks better, but because you can leverage and borrow far more against property, Asset A puts more money to work for every dollar you contribute.
Greater leverage can magnify compounding and improve the return on your own money, although it also increases risk.
To match a property delivering a 20% IRR, a bank deposit would need to pay around 30% before tax.
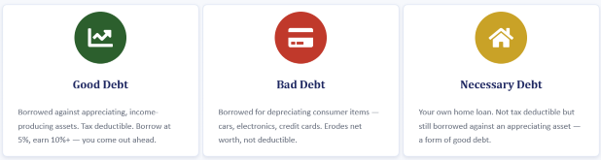
Not all debt is bad debt
Despite what many of us were taught at school and by our parents, debt can be useful when managed carefully.
What matters is what you borrow for.
Why capital growth wins in the end
Take two 30-year-olds. One chases cash flow; the other chases capital growth. After 30 years, the growth investor could finish about 2.3 times further ahead.
An extra $10,000–$20,000 a year in cash flow would certainly help in today's environment, but an extra $3 million in 30 years could make a much bigger difference to your long-term wealth.
The bottom line: know your numbers before you dip your toe in
Our priority is to help investors build wealth with safety and security in mind.
That comes down to a few principles:
- Get the order right, and treat tax benefits as a bonus, not the reason to buy
- Hold for the long term and let compounding do the heavy lifting
- Budget for every cost, model conservatively, and never raid your buffer
- Prioritise capital growth, use leverage wisely, and protect your borrowing capacity
The rules may keep changing, but investors who understand their numbers will be better placed to make sound decisions.
Want to go deeper? Our seminars in Brisbane, Sydney and Melbourne are just $39.99 and include a copy of the book.
And remember: property education like this may be tax-deductible, so ask your accountant.
This article is general information only and doesn't consider your personal circumstances. Speak with a licensed financial adviser, accountant or broker before making any investment, tax or lending decisions.