
Key takeaways
Start with the end in mind. Know how much passive income you need in retirement and build your property strategy around that goal.
Focus on asset quality, not property count. A smaller portfolio of high-quality properties can create more wealth with fewer headaches.
Successful property investing has four stages. Education, accumulation, consolidation and eventually living off your portfolio.
Know when to stop accumulating. Reducing debt and strengthening your asset base become increasingly important as retirement approaches.
Diversification helps protect your wealth. Shares, superannuation and commercial property can complement your residential property portfolio.
Living off equity can help preserve your assets. However, this strategy requires strong capital growth, manageable debt and suitable lending arrangements.
Time and compounding do the heavy lifting. A few well-chosen properties held over the long term can help fund your retirement and create intergenerational wealth.
Are you a property investor wondering what the end game looks like and how to bring it all together?
Most property investors spend a huge amount of time thinking about their next purchase, but far fewer stop to ask the questions that really matter.
How much passive income will I need to retire, how long will it take to get there, and when the time comes, how will I live off my portfolio?
That is the end game.
If you don't know what that looks like, including the specific numbers and milestones, you can't build a plan to get there.
Instead, you end up with more of a buy-and-hope strategy.
Although we call it the end game, it should be one of the first things you think about when you start investing

It's the asset base, not the property count
Michael Yardney often says he would rather own one Westfield shopping centre than fifty properties in a regional town.
Plenty of people boast about owning ten or twenty properties, but that can be a vanity metric.
One property worth $10 million and ten properties worth $1 million each represent the same asset base, and it's the size and quality of that asset base that produces your income later on.
A large number of properties also creates a practical problem in retirement.
Fifteen or twenty properties means more tenants, more maintenance, more risk and, effectively, a part-time job as a property manager.
That's not what most people picture when they think about financial freedom.
Give me a couple of great assets in great locations that largely look after themselves. I'd take that every day of the week.
Start with your financial independence number
Most people know their salary and roughly what their super balance looks like.
Very few know the number that defines their end goal: the passive income they'll require to live the life they want.
That figure simply must be the starting point.
Once you know it, you can work backwards and pull the right levers to get there.
Michael and I covered this in detail in a recent webinar about knowing your financial independence number webinar.
We worked through practical exercises and the three key decisions that can shape your outcome.
What should be in place when you retire?
Ideally, a few things are sorted by the time you stop working.
- A debt-free home. You don't want non-deductible debt in retirement. Some people downsize to clear the mortgage; others use savings or an inheritance.
- A low LVR, not necessarily zero debt. People often talk about retiring with no debt at all, but that isn't essential. Carrying a loan-to-value ratio of around 10–20% can be perfectly fine, provided the portfolio pays that debt down and funds itself.
- Diversified assets. Once you've built a strong property base, it often makes sense to spread into shares, ETFs and commercial property.
- Super working for you. The rules have shifted, but superannuation can still be used effectively, both to grow your wealth and to fund the end game.
The real risk is having significant debt and no income to service it.
You never want to be in that position, which is why bringing the LVR down matters as you approach retirement.
My diversification of assets really only began once I'd built enough of an asset base by investing in property.
That sequence was quite deliberate from an early age: property built the base, and other assets then broadened it.
The four stages of a property investor
- Education. Learning enough to make informed decisions and follow a proven strategy. That's what this whole series has been about.
- Accumulation. Buying quality over quantity. This stage typically takes seven to ten years and builds an asset base that can keep compounding for another decade or more.
- Consolidation. Recognising you have enough property and shifting focus from buying to strengthening.
- Living off your portfolio. Turning the cash machine you've built into the income that funds your lifestyle.
The hardest question in this journey is: how do you know when you've reached consolidation?
You can't simply keep buying, because every new property brings more debt.
Knowing when to stop is just as important as knowing when to start. Consolidating and reducing debt matters just as much as building the asset base.
Your options in the consolidation phase
Once your asset base is sufficient and has enough growth in it to get you to your end goal, the priority changes.
The focus then shifts to paying down debt, and you have several levers to pull.
- Switch from interest-only to principal and interest. If you've used interest-only loans as a tool during accumulation, this is the time to start repaying principal, ideally once rents have risen enough to support the higher repayments.
- Diversify into shares or commercial property. Commercial assets can add stronger cash flow to a growth-focused residential portfolio.
- Use super to buy time. Many investors in their mid-50s or 60s assume they've run out of time. Someone who retires at 65 could draw on their super, which can be tax-free in retirement phase, for the next decade, giving their properties more time in the market to grow. This is a more advanced strategy and needs the appropriate advice.
- Redevelop or add value. This is one of my favourite parts of the cycle. Renovating or redeveloping can boost rent and depreciation. Then you switch to principal and interest so the property looks after itself and keeps paying itself down.
- Sell down, as a last resort. If you're building wealth and a legacy for your family, selling assets should be the final option, not the first.
Case study: modelling a 2039 retirement
We run detailed modelling for clients so they can see what their end game could, and should, look like.
Here's one example, projected to 2039, about 13 years from now.
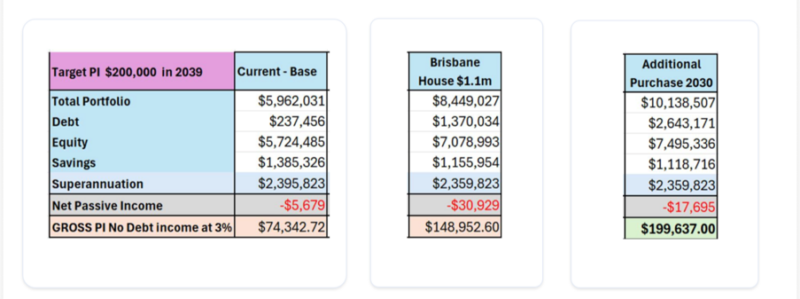
The baseline. The clients own their home and one investment property. Their passive income goal in today's dollars is $150,000 a year. Once we factored in inflation, that target became $200,000 a year by 2039.
- Also read:Latest Property Price Forecasts. Australian Property Market Outlook 2026-2027: Navigating a Market Correction

- Also read:Brisbane Property Market Forecast [2026 & Beyond] – What The Olympics Decade Means for Investors.
- Also read:Melbourne property market forecast for 2026 & 2027 | Separating the fundamentals from the sentiment
- Also read:Sydney property market forecast for 2026 and 2027 | Why the short-term softness is a long-term opportunity
- Also read:Adelaide housing market update | October 2026

Doing nothing. Their portfolio would be worth almost $6 million with very little debt. Yet even after using savings to clear the debt and investing their super, they'd generate only around $75,000 a year. That's well short of their goal. It concerns me, because I'm not confident the pension will look the same in 15 or 20 years, and I suspect super will face more tax over time.
One more property. Adding a $1.1 million Brisbane house, which is achievable in today's market, lifts their projected income to about $150,000. Had they not allowed for inflation, they'd probably feel comfortable here. In reality, they'd still be $50,000 short.
Two more properties. Our modelling showed they could afford another, similar purchase in 2030. With that, by 2039 they reach their passive income goal. Once the debt is cleared, they can contribute to super, draw a solid income from it, and live off their property portfolio at around a 3% return.
That's two additional properties on top of what they already own. It's a measured strategy rather than a race to accumulate properties.
It's time, compounding, leverage and growth doing the heavy lifting.
Living off equity: having your cake and eating it too
Living off equity is a strategy Michael talks about, and it resonated with me the first time I read his book.
The idea is simple: instead of selling, you borrow against the growth in your portfolio to fund part of your lifestyle.
Why avoid selling? I've got kids, and I'd love to hand my portfolio down to them intact.
Selling can trigger capital gains tax and means giving up future growth, while borrowing against equity can allow the portfolio to keep compounding as you draw on part of its value.
Here's how it looked in the days when lenders were far more flexible:
- A $10 million portfolio with $4 million of debt, a 40% LVR
- Net rental income of about $150,000 a year
- An equity drawdown of a further $150,000 a year
- Portfolio growth of 5% a year, or about $500,000
That's a $300,000 lifestyle income while the portfolio still grows by $500,000 a year.
In this example, debt rises more slowly than asset values, so the LVR continues to fall.
The catch. It's much harder today. Back then you had low-doc loans and even NINJA loans (no income, no job, no assets).
Accessing equity is much harder today, and lenders assess serviceability, income and risk carefully. A low LVR can help, but it does not guarantee approval.
Rental income, other income sources and the overall financial position all matter when a lender assesses an application.
It also only works with quality assets that compound at strong rates, spread across markets that grow at different times.
Melbourne went largely sideways for about seven years, and Perth and Brisbane had their own flat decade before that.
A portfolio spread across Brisbane, Melbourne and Sydney can help balance out those different market cycles.
Note that the case study above didn't rely on living off equity.
Using savings and super to clear debt, without selling a property, and still living off passive income is first prize.
Downturns are the fee for admission
Every property cycle brings unexpected challenges and downturns. They are part of investing.
If property rose every single year, with no scary moments, no rate rises and no inflation, everyone would be doing it and getting a free ride.
Markets move in cycles, as they always have.
To ride them out:
- Hold assets in the right structures and ownership
- Have a clear finance and tax strategy
- Take a long-term mindset
Simple, but not easy
Everything we have discussed is simple to explain.
You may well be nodding along, but simple isn't the same as easy, especially in today's market.
It takes courage to put your hard-earned income on the line when everything around you seems to be falling apart.
Around 92% of property investors own only one or two properties, and as the case study shows, that may not be enough to create the level of long-term income they're aiming for.
To get a different result, you need to do things differently:
- Listen to people who have built substantial portfolios with a proven strategy
- Set real goals and follow a known, trusted system
- Treat your investing like a business and grow it one property at a time
- Build asset value and quality, not a property count
- Work towards a debt-free home and a lower LVR
- Diversify your assets and use super as a key strategy
- Consider living off equity if lending conditions allow when you get there
Property investing is ultimately about what property can help you achieve.
The goal is the freedom to live the life you want, supported by the assets you've built.
Start with the end in mind, understand your baseline, identify the gaps and plug them, and give yourself the best chance of reaching your long-term goals.
For me, it's also about leaving a legacy for the next generation, because they're going to need it.
This article contains general information only and does not take into account your personal objectives, financial situation or needs. Consider seeking personal financial, tax and legal advice before acting on it.