
Key takeaways
Falling property prices create opportunities for home buyers. Lower prices, less competition and more choice give buyers greater negotiating power.
Know your numbers before buying. Allow for higher interest rates, upfront costs and a financial buffer to protect yourself against unexpected expenses.
Renting is becoming increasingly expensive. Rising rents and potential rental shortages make homeownership worth considering for those who can afford it.
Think long-term when buying property. Property markets move in cycles, and temporary price falls matter less when you have a long-term investment strategy.
Treat your first home as an investment. Buying the right property can help you build equity and become a stepping stone towards a multimillion-dollar portfolio.
Don't let saving a larger deposit hold you back unnecessarily. Paying lenders mortgage insurance could help you enter the market sooner.
Use debt strategically to build wealth. An interest-only loan and offset account may help preserve capital for future investments while keeping your options open.
Are you looking to buy a home but feeling uncertain about what lies ahead?
Investors may not want to hear that prices are falling, but if you are a home buyer, that should be music to your ears.
The next three to six months could present a rare opportunity and set you up for decades, if you do some very smart things.
These are strategies I have used myself, rather than ideas that sound good in theory.
I started my journey more than two decades ago as a home buyer, and my first investment was my own home and it snowballed from there.
Here is how to go from home buyer to millionaire, starting with the market we are in today.

The best investment you can make is $2
Can you hear it?
There is so much noise and confusion out there at the moment.
Negative headlines, gloomy talk at dinner parties and barbecues, and a constant stream of panic on social media.
Negativity sells, and it will continue to keep selling for the foreseeable future.
Rather than buying into all the hype and riding the roller coaster, pop your ear plugs in and focus on the things that actually move you forward.
Know your numbers
Unless you have been living on another planet, rates have risen for the fifth time this year.
The cash rate is now 4.85%, and each 0.25% rise adds roughly $100 a month to the repayments on a $700,000 loan.
Knowing those numbers will help you establish your limits and boundaries.
Just as important, a property costs more than the price on the contract, on a $750,000 home, budget for these upfront costs on top of your deposit:
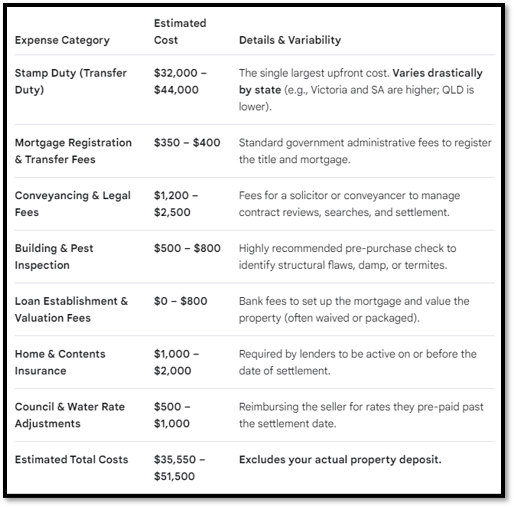

Tip: A word of advice, always get a building and pest inspection, even on a brand-new property.
Don't assume shiny and new means there are not any issues lurking beneath: handover inspection services exist for exactly this reason.
Once you know your numbers, put a buffer in place and stress test your budget for another rate rise or two.
If you can do that, keep those ear plugs in and keep moving forward.
What’s the alternative: keep renting
Rents have risen around 50% since the pandemic, and renters now spend a record 33.1% of household income on rent.
I suspect if you are currently renting over the last 5 years, you already know this.
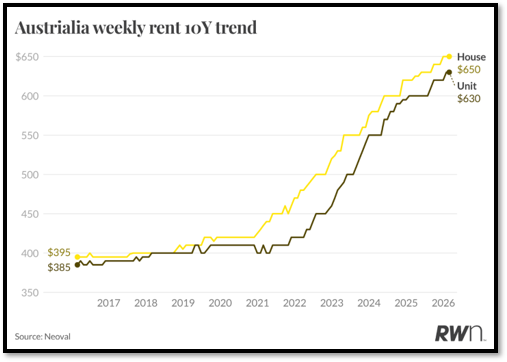
With the new government policies announced in May, I expect the upward pressure to continue.
The Budget changes will discourage investors from buying established homes to rent out, which could tighten rental supply further.
Demand will continue to rise with strong population growth, while a shortage will remain as investors exit the market.
Remember: rent still pays off a mortgage, it's just not yours.
If you have the option to buy but choose to keep renting, think twice.
| City | Change in values, May to October 2026 |
| Sydney | -7.9% |
| Melbourne | -5.6% |
| Brisbane | -3.9% |
| Adelaide | -3.0% |
| Perth | -1.4% |
| Capital cities | -5.3% |
Source: Cotality : from May to October 2026.
I suspect the market will find some kind of equilibrium, but I don't expect prices to rise anytime soon.
For buyers, that means more stock, more choice and more negotiating power, the complete opposite of this time last year.
Negative equity: don't panic
I know some people are in negative equity right now, owing more than their home is worth.
But please, don't panic, selling would crystallise that loss.
Instead, remember that property is a very forgiving asset and you would have purchased with a long-term view, so what happens in the next six months won't matter.
Even 5 years from now, the market, interest rates and the government, will have moved on and we will be well into a new cycle.
Three things give you holding power:
- A cash buffer, so a rate rise or a surprise bill never forces your hand.
- A long time frame. Think decades, not months.
- A quality asset that recovers first, in an area with plenty of owner-occupiers. Home buyers keep a floor under a market and keep demand stronger when it turns.
The long view: house prices since 1881
If you're thinking long term, look at what Australian house prices have lived through since 1881.
Wars, depressions, recessions, the GFC, mining booms and COVID-19, yet it still forges ahead.
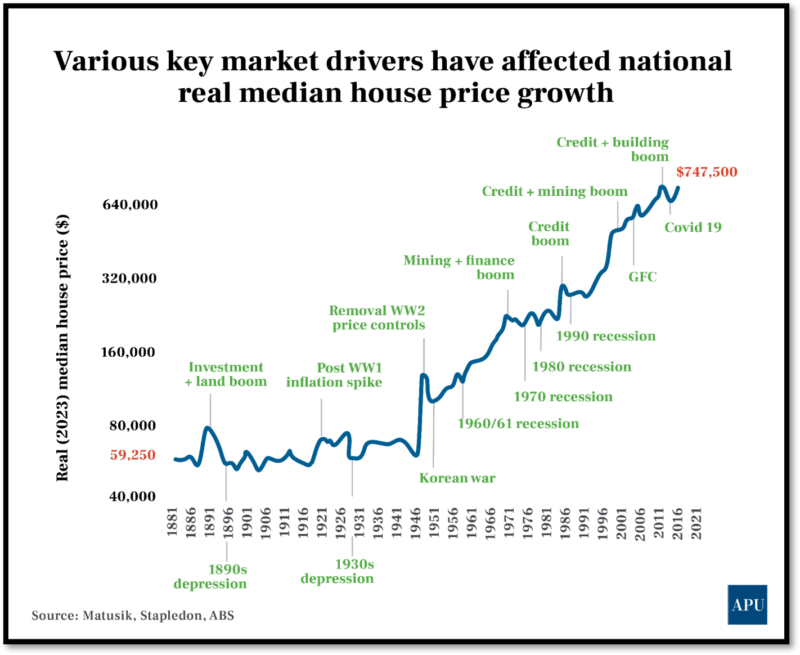
When COVID hit, headlines warned of a mortgage cliff and predicted prices would drop 40%. Instead, the median house price today is $954,405.
Prices may dip again from here, but I wouldn't mind betting that in 10 or 20 years we will be back at record highs.
Ups and downs are part of every cycle, but it can be hard to grasp when you're just getting into the market, which is why a longer term perspective matters.
Why your timing is perfect
Compare the market a year ago with today, and with where it is likely heading:
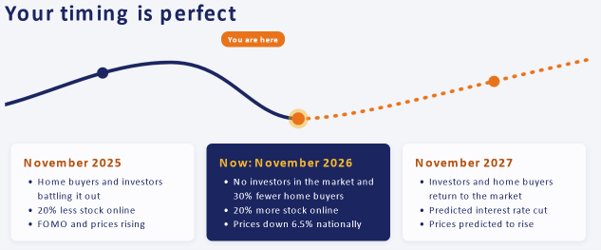
If I had told you a year ago that you would face less competition and lower prices, while having more stock available, you would have jumped at it.
That is exactly the market in front of you now.
- Also read:Guide to Downsizing a House in Australia
- Also read:Latest Property Price Forecasts. Australian Property Market Outlook 2026-2027: Navigating a Market Correction

- Also read:Brisbane Property Market Forecast [2026 & Beyond] – What The Olympics Decade Means for Investors.
- Also read:Melbourne property market forecast for 2026 & 2027 | Separating the fundamentals from the sentiment
- Also read:Sydney property market forecast for 2026 and 2027 | Why the short-term softness is a long-term opportunity
If CBA and most market commentators are right, by November 2027 investors will be back in some shape or form, with more certainty and confidence in the market.
So, use the next three to six months to get your advantage, get your ducks in a row and take action.
Now is your time to act.
Treat your home as an investment, because it is
Is your first home going to be your forever home? It's highly unlikely.
Treat it as an investment you happen to live in, and it can become the stepping stone to a multimillion-dollar portfolio.
That is exactly what I did.
Sometimes that means sacrifice and not getting a 4-bedroom house or buying straight into your dream suburb.
Buy in the suburb you can afford, where your money works hardest, and choose a home that meets most of your needs.
Tip: Pay lenders mortgage insurance
Lenders mortgage insurance (LMI) is a necessary evil.
On a $1 million property, saving up to a 15% or 20% deposit could take 50 or 60 months, but paying LMI could get you into the market today.
So, allow for that cost, weigh up the fee rather than automatically waiting.
This time next year the market is likely to look very different, and you could miss your opportunity if you are taking months or years to avoid paying LMI.
Don't pay off your home loan (if it isn't your forever home)
That's not what Mum and Dad told me and may not be the advice they gave you either.
But my Mum and Dad weren't multimillion-dollar property investors, so I took advice from someone who was.
Their advice was not to pay off my home, but to use debt strategically.
The odds that your first home will be your forever home are low, especially for younger buyers:
| Generation | Forever home | Stepping stone |
| Baby Boomers | 41% | 35% |
| Millennials | 31% | 54% |
| Gen Z | 17% | 47% |
So, if this is not your forever home, why rush to pay it off?
Paying interest only on an $850,000 property could free up around $500 a month in a high-rate environment.
Saved for five years, that is about $35,700, add some equity from your home and you could have the deposit for your next property.
That $500 isn't spending money, though. Keep some for emergencies, and put the rest towards another property, shares or ETFs so your asset base keeps growing.
Paying down debt too quickly can cost you time and limit your ability to build a wider asset base.
Tip: Use an offset account
If I'm wrong and you still want to pay down your home, do it.
But consider an interest-only loan, for say three years, and put everything you would have paid off the principal into an offset account linked to your home loan.
Put your salary and all your income into that offset to reduce the interest you pay, then take your expenses out of it.
Those little things can add up and save you thousands of dollars.
The money in your offset will also be transportable rather than locked in.
If this becomes your forever home, you can pay the loan down later, if it doesn't, you can take that capital to your next home, instead of leaving it locked into a property.
This is a mistake I see many home buyers make.
When I started investing, I realised I wasn't in my forever home.
I needed capital to grow my asset base, and paying down my mortgage wasn't the answer.
The summary: your challenges and your strategies
There are many challenges to overcome before you move forward.
Doing so is essential, as it will give you the confidence and direction to avoid the noise and take action.
The cash rate has risen to 4.85% and the rate your bank charges will be more, so allow for this, along with another rise or two on your modelling.
Prices are falling and will likely do so for the short term, do not see this as an obstacle, but rather an opportunity.
If you find yourself in negative equity, remember that you have committed to holding the property for the longer term.
Don't panic. You will get through it, and in 10 years it won't matter.
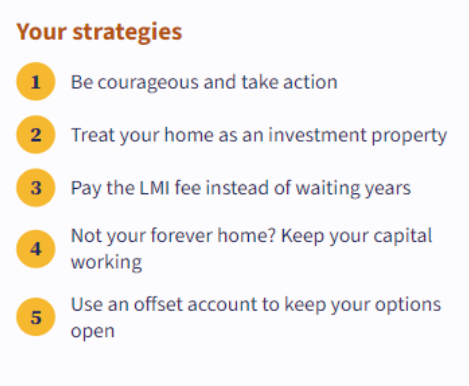
Your strategies should be:
Ready to take the next step?
We work with a lot of home buyers who want to set themselves up by buying their home first.
Right now, we're seeing an amazing number of off-market opportunities across Brisbane, Sydney and Melbourne, from owners who don't want to go to market.
Whether you need a strategy or you're ready to buy now, we're ready to help.
Click here to find out more.