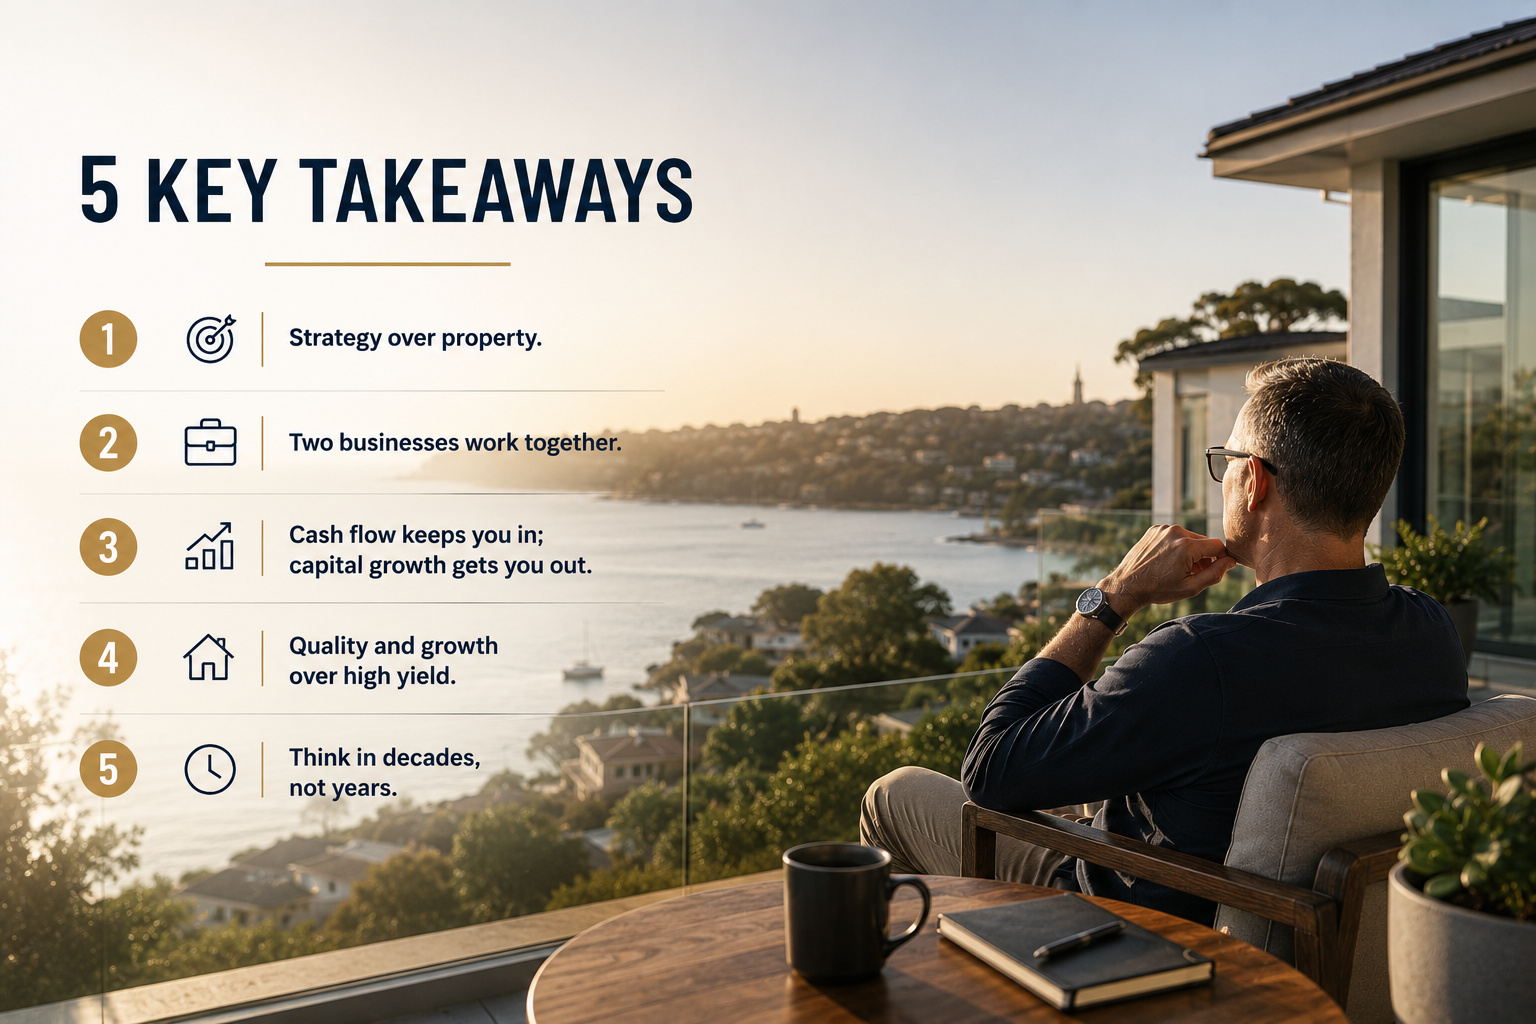

Key takeaways
Property success starts with strategy, not property selection. Most investors focus on buying the next property when they should be building a long-term plan for wealth creation.
Think of investing as running two businesses. Your cash flow business funds your lifestyle and portfolio, while your property portfolio builds long-term wealth through capital growth.
Cash flow keeps you in the game; capital growth creates wealth. A strong income allows you to hold quality assets long enough for compounding and leverage to do the heavy lifting.
High-yield properties often sacrifice long-term growth. Many investors chase rental income, but investment-grade properties with superior capital growth typically deliver better wealth outcomes over time.
Successful investing happens in phases and requires patience. First build a high-growth asset base, then reduce debt, and ultimately live off your portfolio's income. The investors who succeed think in decades, not years.
Most investors who come to me think about property the wrong way, and it's costing them dearly.
They're focused on finding the right property, when what they really need is the right strategy - one that accounts for both how they stay in the game financially and how they eventually build enough wealth to leave it.
After five decades of investing and advising others, I've come to see successful property portfolio building as running two separate businesses simultaneously.
Understanding the difference between these two businesses - and the role each plays - is one of the most important shifts an investor can make.
Why most investors get stuck
You've probably heard the statistic that 92% of property investors never get past their first or second property. I've been quoting it for years, and it remains stubbornly accurate.
There are many reasons for this, but one of the biggest is the lack of a strategic plan that accounts for the long game. They buy a property or two, run into cash flow pressures, and find themselves unable to continue growing the portfolio.
The dual-business model I'm about to describe is designed to prevent exactly that.
Business One: your cash flow engine
The first business in this model is your cash flow business - and for most people, this is simply their job, their career, or a business they run.
I know that might seem too simple, but here's why it matters: residential property in Australia is a low-yielding, high-growth asset class.
That's not a flaw - it's actually why it builds so much wealth over time - but it does mean that rental income alone won't cover your living expenses or service the debt you need to grow a serious portfolio, at least not in the early years.
Your career or business is what finances your property ambitions. It's what pays the mortgage when rates rise, covers vacancy periods, and gives lenders the confidence to keep lending to you.
Cash flow keeps you in the game. Without it, you're often forced to sell, and there goes the wealth in your asset base.
Business Two: your capital growth property portfolio
The second business is your property portfolio, which I like to call your capital growth business.
This business is all about acquiring investment grade properties that will appreciate in value over time, turning your portfolio into a wealth-generating cash machine.
The problem is property investment is a long game.
The real magic happens over multiple property cycles, and it can take 20 to 30 years to build a sufficiently large asset base to become the cash machine you desire.
During this time, market appreciation, leveraging and compounding work together to significantly increase the value of your properties.
As property values rise, so does your equity. This increased equity can then be used to acquire more properties, creating a snowball effect that accelerates the growth of your portfolio.
Eventually, your property portfolio will reach a point where it can generate substantial passive income, potentially replacing your need for the cash flow business entirely.
At this stage, your portfolio becomes a significant source of wealth and financial security.
Integrating the two businesses
While these two businesses serve different purposes, they are interconnected and support each other.
As I said...cash flow keeps you in the game; capital growth gets you out of the rat race.
- Also read:Latest Property Price Forecasts. Australian Property Market Outlook 2026-2027: Navigating a Market Correction

- Also read:Brisbane Property Market Forecast [2026 & Beyond] – What The Olympics Decade Means for Investors.
- Also read:Melbourne property market forecast for 2026 & 2027 | Separating the fundamentals from the sentiment
- Also read:Sydney property market forecast for 2026 and 2027 | Why the short-term softness is a long-term opportunity
- Also read:This week’s Australian Property Market Update – Latest Data, State by State September 29th 2026
The problem is too many beginning investors look for cash flow investments.
At first glance, high rental yields seem like a dream come true. Who wouldn't want a property that brings in a hefty rental income every month?
These investors are thinking about the here and now, rather than the long term, meaning they buy properties that may solve a short-term problem but won’t give them the long-term results they hope for – in general, higher cash flow properties have poorer long-term capital growth, which means they don't allow you to build significant long-term wealth.
And don’t forget that high yielding properties also come with higher tax burdens.
If you're a high income earner, a significant portion of that rental income goes straight to the government.
Capital growth, on the other hand, is not taxable while you hold the property - and even when you sell, there are concessions available.
The three phases of a property portfolio growth
A successful property investment journey moves through three distinct phases, and understanding where you are in the journey helps you make better decisions.
The first phase is the capital growth phase, where you focus on building your asset base with investment-grade properties across multiple cycles. This phase requires significant leverage and is dependent on your cash flow business to support it. This is where patience really matters.
The second phase is reducing your loan-to-value ratios. Once you've accumulated a sufficiently large asset base, you start paying down debt - either through the portfolio's own income or by redirecting earnings. As equity builds and debt reduces, the portfolio's net cash position improves.
The third phase is living off your property portfolio. This is what the whole journey is working toward - a point where the rental income, minus expenses and any remaining debt costs, is sufficient to support your lifestyle without needing to work.
Most investors underestimate how long the first phase takes, and that impatience leads them to make compromises in property selection that slow everything down.
The balancing act
None of this means you should ignore cash flow entirely when selecting properties. You do need to be able to service the debt, and lenders will want to see that serviceability before they'll keep lending.
The right approach is to buy the best quality, investment-grade, high-growth property you can afford while still being able to service the debt.
That means being realistic about your borrowing capacity, having adequate buffers, and building the portfolio at a pace your cash flow business can support.
Quality over quantity has always been my view. You don't need a dozen average properties. A handful of the right ones, held for long enough, will do far more for your financial future.
Thinking in decades, not years
The thing I keep coming back to is that the investors who build real wealth are the ones who think in decades.
They understand that the cash flow business is a temporary vehicle - something that enables the capital growth business to compound over time. They don't try to replace their income with rental yields too early. They stay patient, stay invested, and let time do most of the work.
The dual-business model isn't complicated. But it does require discipline, a clear plan, and a willingness to play a long game when everyone around you is focused on short-term returns.
If you'd like help thinking through where your cash flow business and your capital growth portfolio should be heading, the team at Metropole would be glad to talk.
We've been helping investors build this kind of strategic plan for decades, and we'd love to help you build yours.
Click here now and organise a chat with one of our wealth strategists to see how you can take advantage of this approach.