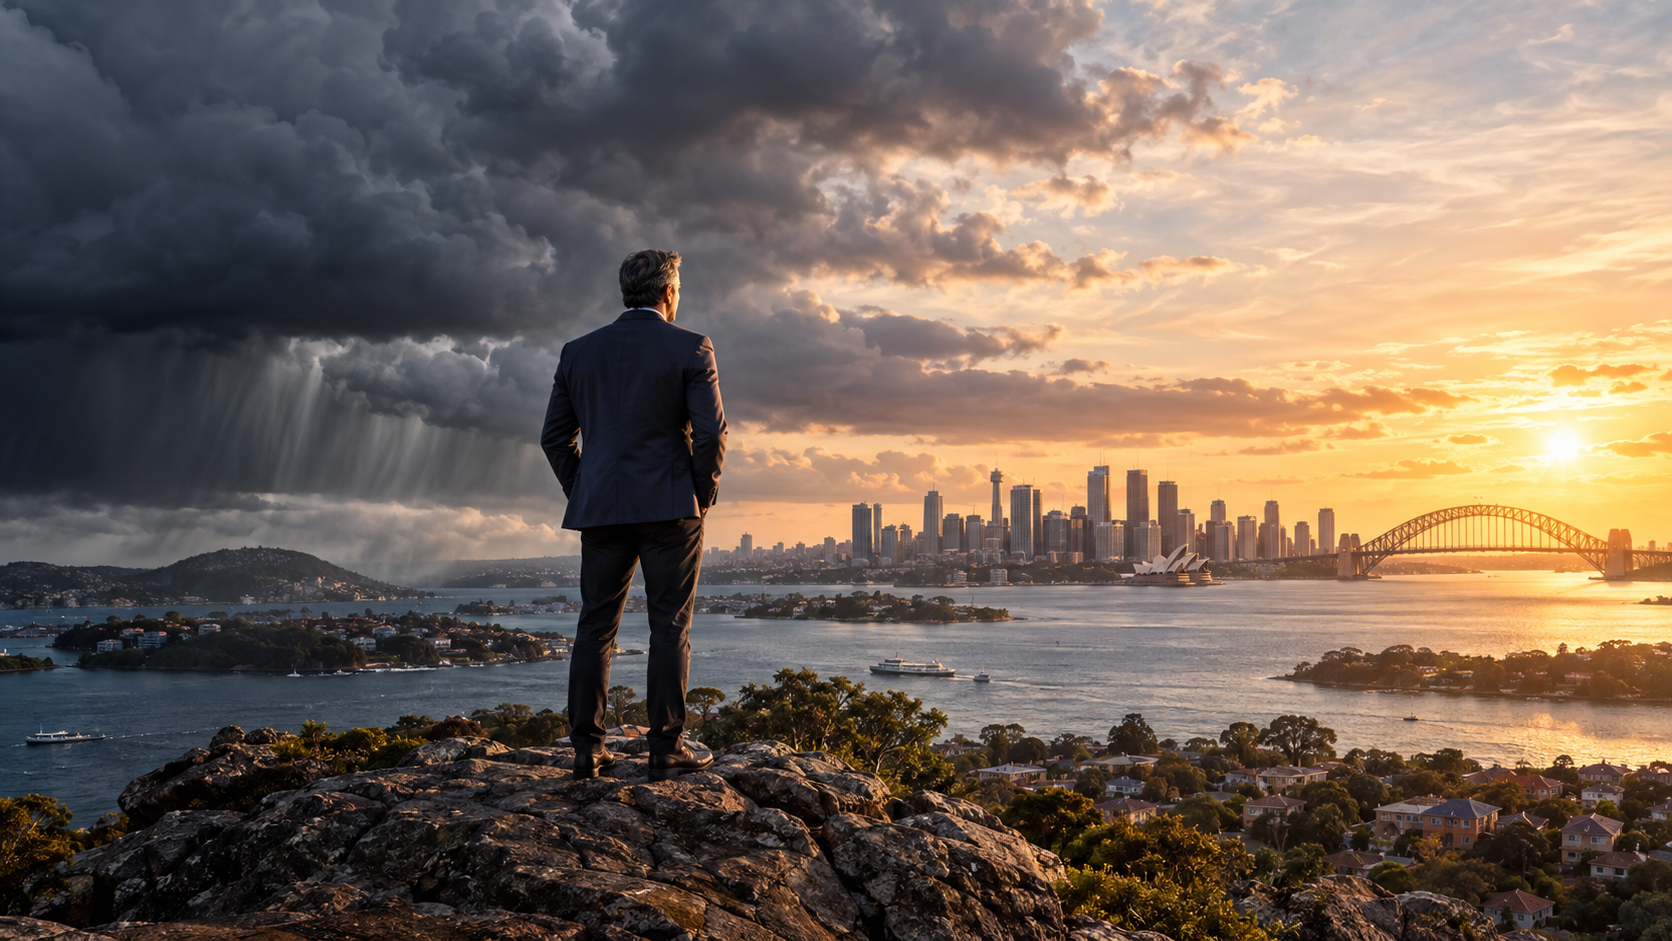

Key takeaways
X-factors are inevitable. Investors can't predict every shock, but they can prepare for uncertainty.
Markets rarely move in straight lines however, recency bias can lead investors to assume today's conditions will continue indefinitely.
Strong strategies are built to adapt. Financial buffers, manageable debt and quality assets help investors ride through unexpected changes.
Demographics provide valuable clues about the future. Long-term trends can help investors look beyond short-term market noise.
Resilience matters more than perfect forecasting. Successful investors focus on fundamentals and adjust when circumstances change.
What if the biggest risk to your wealth isn't choosing the wrong property, paying a little too much, taking out the wrong loan, or even buying at the wrong stage of the property cycle?
What if the biggest risk is something you haven't even considered yet?
I've been investing for more than 50 years, and during that time I've lived through recessions, double-digit interest rates, credit squeezes, stock market crashes, banking crises, wars, changes of government, major tax reforms, the Global Financial Crisis, a once-in-a-century pandemic and more predictions of an Australian property crash than I could possibly count.
And there's something I've learned from all of this...
The events that often have the greatest impact on our wealth are rarely the ones everyone is talking about today. They're the developments that sit outside our forecasts, change the assumptions on which those forecasts were based and force us to rethink what comes next.
Way back in the early 1980s, economist Dr Don Stammer taught me to watch for something he called the X-factor.
Today, many people would loosely describe these events as "black swans", although leading demographer Simon Kuestenmacher makes an important distinction between the two.
An X-factor doesn't necessarily need to be completely unimaginable. It can be an event, trend or technology that was already visible, but whose timing, scale or consequences weren't properly appreciated.
As Simon explains:
"It's an event, a trend, a technology that produces consequences that just change things."
COVID is an obvious example. Epidemiologists had warned about the possibility of a pandemic for decades, so the concept itself wasn't unimaginable.
What couldn't be forecast was exactly when it would occur, how governments would respond, how long borders would close, what would happen to migration, how households would behave or how dramatically economic policy would change.
And that's an important distinction for property investors because the lesson isn't that we should somehow become better at predicting the unpredictable. We need to become better at preparing for it.

For weekly insights, subscribe to the Demographics Decoded podcast, where we will continue to explore these trends and their implications in greater detail.
Subscribe now on your favourite Podcast player:
Why investors keep getting the future wrong
Human beings aren't particularly good at dealing with uncertainty.
We naturally assume tomorrow will look reasonably similar to today, and we give far too much weight to whatever has happened most recently.
Simon calls this the "straight line fallacy."
Property investors do this all the time. Prices rise strongly for a couple of years, and suddenly people believe they'll keep rising at the same pace. Prices fall for several months, and commentators start extrapolating another year or two of declines.
Interest rates rise, and borrowers assume they'll remain high indefinitely. Rates fall, and investors begin structuring their finances as though cheap money has become permanent.
Of course, economies and property markets don't move in straight lines, and X-factors are particularly disruptive because they change the trajectory everyone had become comfortable extrapolating.
Yet sometimes the developments that surprise us aren't really surprising at all.
Demographics gives us one of the clearest examples.
Population ageing is hardly a secret. Simon regularly points out that Australia's population aged 85 and over is expected to roughly double over the next 14 years. This means enormous additional demand for aged care, healthcare, suitable housing and workers.
None of that should surprise us when it arrives. As Simon puts it, sometimes "the X-factor just sneaks up on us."
We know it's coming, but because it doesn't feel urgent today, governments, businesses and individuals postpone dealing with it until eventually the predictable becomes a crisis.

Tip: For investors, the distinction matters. There are genuine surprises we can't forecast, and there are slow-moving structural changes we can see quite clearly but fail to prepare for. A sound investment strategy needs to recognise both.
Australia has been here before
Looking back through Australia's economic history provides some useful perspective.
The floating of the Australian dollar in 1983 fundamentally changed our exposure to international capital.
The 1987 stock market crash demonstrated how quickly financial turmoil overseas could reach Australian investors.
The Asian Financial Crisis, the dot-com crash, the GFC, the pandemic and more recent geopolitical conflicts each arrived with their own predictions about what would happen next.
Frequently, those predictions were wrong.
The Global Financial Crisis provides a particularly useful example - it devastated parts of the American and European financial systems, yet Australia experienced a very different outcome.
Timely government stimulus, bank guarantees, continuing Chinese demand for Australian resources and a financial system that entered the crisis in relatively sound shape meant we absorbed the shock differently.
As Simon points out, Australia's economic model has some useful underlying strengths. We export resources, energy, agricultural products and services that a growing world continues to require.
That doesn't make us immune from global shocks because Australia remains a relatively small, open economy exposed to international events.
But the impact of an X-factor depends heavily on the conditions that existed before it arrived and how governments, businesses and households respond afterwards.
That's why simply reading a frightening international headline and extrapolating the same outcome to Australian property markets can lead investors badly astray.
The real skill is adjusting when the facts change
COVID taught us something else about dealing with X-factors.
During the early months of the pandemic, almost everything we thought we knew was changing rapidly.
We didn't initially understand how serious the virus would become, how long borders would remain closed or what the economic consequences would be. Governments, businesses and households were forced to continuously update their assumptions.
Simon believes this ability to adjust is critical:
- Also read:Latest Property Price Forecasts. Australian Property Market Outlook 2026-2027: Navigating a Market Correction

- Also read:This week’s Australian Property Market Update – Latest Data, State by State September 29th 2026
- Also read:Brisbane Property Market Forecast [2026 & Beyond] – What The Olympics Decade Means for Investors.
- Also read:Sydney property market forecast for 2026 and 2027 | Why the short-term softness is a long-term opportunity
- Also read:Melbourne property market forecast for 2026 & 2027 | Separating the fundamentals from the sentiment
"You cannot just sit still, but you can also not move forward with sheer confidence of what's going to happen."
That's an excellent way of thinking about property investment as well.

Note: Successful investors don't constantly change their strategy every time a new headline appears, because that would replace long-term investing with speculation. However, they also shouldn't stubbornly cling to assumptions after the evidence has changed.
There's an enormous difference between having a strategy and being inflexible.
At Metropole, we've always told our clients to expect their plans not to go exactly according to plan. That might sound strange coming from someone who spends so much time talking about strategic planning, but it's precisely why planning matters.
We can't know what interest rates will be in seven years. We don't know what governments will do to property taxes in ten years. We don't know when the next recession, geopolitical conflict, technological breakthrough or credit squeeze will occur.
Rather than relying on precise forecasts, I prefer to work with expectations and build enough flexibility into the strategy to accommodate different outcomes.
This means financial buffers, manageable debt, appropriate ownership structures, buying investment-grade assets with multiple drivers of demand, and maintaining the financial capacity to continue holding those assets when circumstances don't unfold exactly as expected.
When X-factors collide
Another complication is that unexpected events rarely occur neatly one at a time. Sometimes they arrive in clusters.
In recent years we've seen rapid interest rate changes, geopolitical conflicts, dramatic swings in migration, significant policy changes and rapid advances in artificial intelligence occurring simultaneously.
These forces interact with one another, making the future even harder to model.
Simon argues that when complexity increases, the sensible response is to step back and identify the fundamentals that remain relatively stable.
That's particularly useful advice for property investors. When forecasts become increasingly complicated, I return to some fairly simple questions.
Where are people going to live? Where are jobs being created? Which locations will attract growing numbers of higher-income households? Where is developable land genuinely scarce? Which neighbourhoods have the infrastructure, amenities and lifestyle characteristics people with increasing disposable incomes will be prepared to pay a premium for? And which properties will remain difficult to replicate?
These aren't really predictors of short-term price movements. They're structural questions designed to identify assets that should remain desirable through multiple economic cycles.
Artificial intelligence provides a fascinating example because everyone knows it's coming, yet nobody knows precisely what its consequences will be.
As Simon says, AI may change almost everything while leaving some fundamental human behaviours remarkably unchanged. People will still form relationships, have families, change jobs, grow older and need somewhere to live.
AI could transform productivity, employment patterns and entire industries, but it could also change how investors behave.
Investors today have access to more data than at any point in history, and algorithms can analyse suburb performance, rental yields, migration patterns, supply pipelines and historical growth within seconds.
That's useful, but there's a danger. If thousands of investors use similar models trained on similar historical datasets, they'll often reach similar conclusions and crowd into the same supposedly "hot" markets, helping create the very short-term boom their models predicted.
Data is valuable, and AI will make it even more useful, but property investment still requires perspective, context and judgement.
Historical data tells you what happened under yesterday's conditions. It doesn't automatically tell you how human beings will respond when tomorrow's assumptions change.
X-factors can create opportunities too
We usually discuss X-factors as threats, yet some of the most powerful surprises in history have dramatically improved living standards.
Technological breakthroughs have lifted productivity, new infrastructure has transformed previously inaccessible locations, and new export markets have created enormous national wealth.
Simon believes productivity improvements could become an important positive X-factor for Australia.
Cheaper energy, for example, could make Australian manufacturing considerably more competitive.
Modern construction methods, prefabrication and improved building technology could increase the speed at which homes are delivered and potentially reduce construction costs.
Better infrastructure could improve productivity and unlock new economic opportunities, while AI itself may become an important productivity enhancer. In industries such as aged care, the biggest benefit may have little to do with futuristic robots and much more to do with reducing administrative workloads so workers can spend more time providing actual care.
These improvements matter because a more productive economy ultimately creates more opportunities for businesses, workers and investors.
And there's another type of X-factor investors often overlook: the one that happens within their own lives.
Illness, divorce, redundancy, the loss of a business partner or an unexpected financial obligation can alter your circumstances far more quickly than a change in interest rates.
Fortunately, personal X-factors can also be positive, such as a promotion, inheritance, successful business venture, stronger-than-expected investment returns or children becoming financially independent.
Tip: That's why a financial strategy should never be constructed solely around forecasts for interest rates or property prices. It needs to be built around your stage of life, income, financial capacity, risk tolerance and risk capacity.
The one thing investors keep getting wrong
Over the years I've watched investors spend enormous amounts of time trying to predict exactly what will happen next.
When will interest rates fall? Where will property prices be next year? Which suburb will boom? What will the government do? What will happen to migration?
These are reasonable questions, but there's a limit to how much certainty anyone can provide.
The next X-factor will come along eventually, and by definition we probably won't fully appreciate its consequences beforehand.
So rather than trying to predict every surprise, a better approach is to own the right assets and structure your finances so you can withstand the surprises when they inevitably arrive.
Over my 50 years of investing, I've watched Australia navigate recessions, extraordinarily high interest rates, credit squeezes, banking crises, political changes, new taxes, wars, a pandemic and repeated predictions that our property markets were about to collapse.
Yet our population continued growing, businesses adapted, people continued working, households continued needing somewhere to live and well-located investment-grade properties continued benefiting from Australia's long-term economic and demographic growth.
There will undoubtedly be another X-factor, and another one after that. Some will create challenges, while others will create opportunities we can't yet imagine.
Note: The investors who prosper over the decades ahead won't necessarily be those who predict each one correctly. They'll be the ones who understand the fundamentals, maintain sufficient financial buffers, own quality assets and remain flexible enough to adjust when circumstances change.
Because uncertainty isn't something investors eventually overcome. It's simply part of the journey of building wealth.