
Key takeaways
Former rentals account for more than 40% of newly listed Melbourne homes for sale, according to the latest PropTrack investor report.
Investor sales don’t automatically translate into an equivalent loss of rental homes, but weaker replacement buying creates a risk for rental supply.
Melbourne’s median advertised rent is $600 a week, up 5.3% over the year to September 2026.
Policies that discourage rental investment risk pushing rents higher unless new supply and falling rental demand offset the impact.
How do we expect to make renting more affordable if we keep making the provision of rental housing less attractive?
That’s the concern raised by the latest evidence of Melbourne’s investor sell-off, and I believe tenants have good reason to worry about where it could lead.
Recently, realestate.com.au reported: “Investors made up more than 40 per cent of newly listed homes for sale in Melbourne”.
The article draws on the PropTrack Terri Scheer Investor Report and notes fewer investors buying established homes, alongside the ongoing Victorian investor exodus.
To me, the warning is that rents will keep rising as owners sell, while the appetite to replace them is weakening.
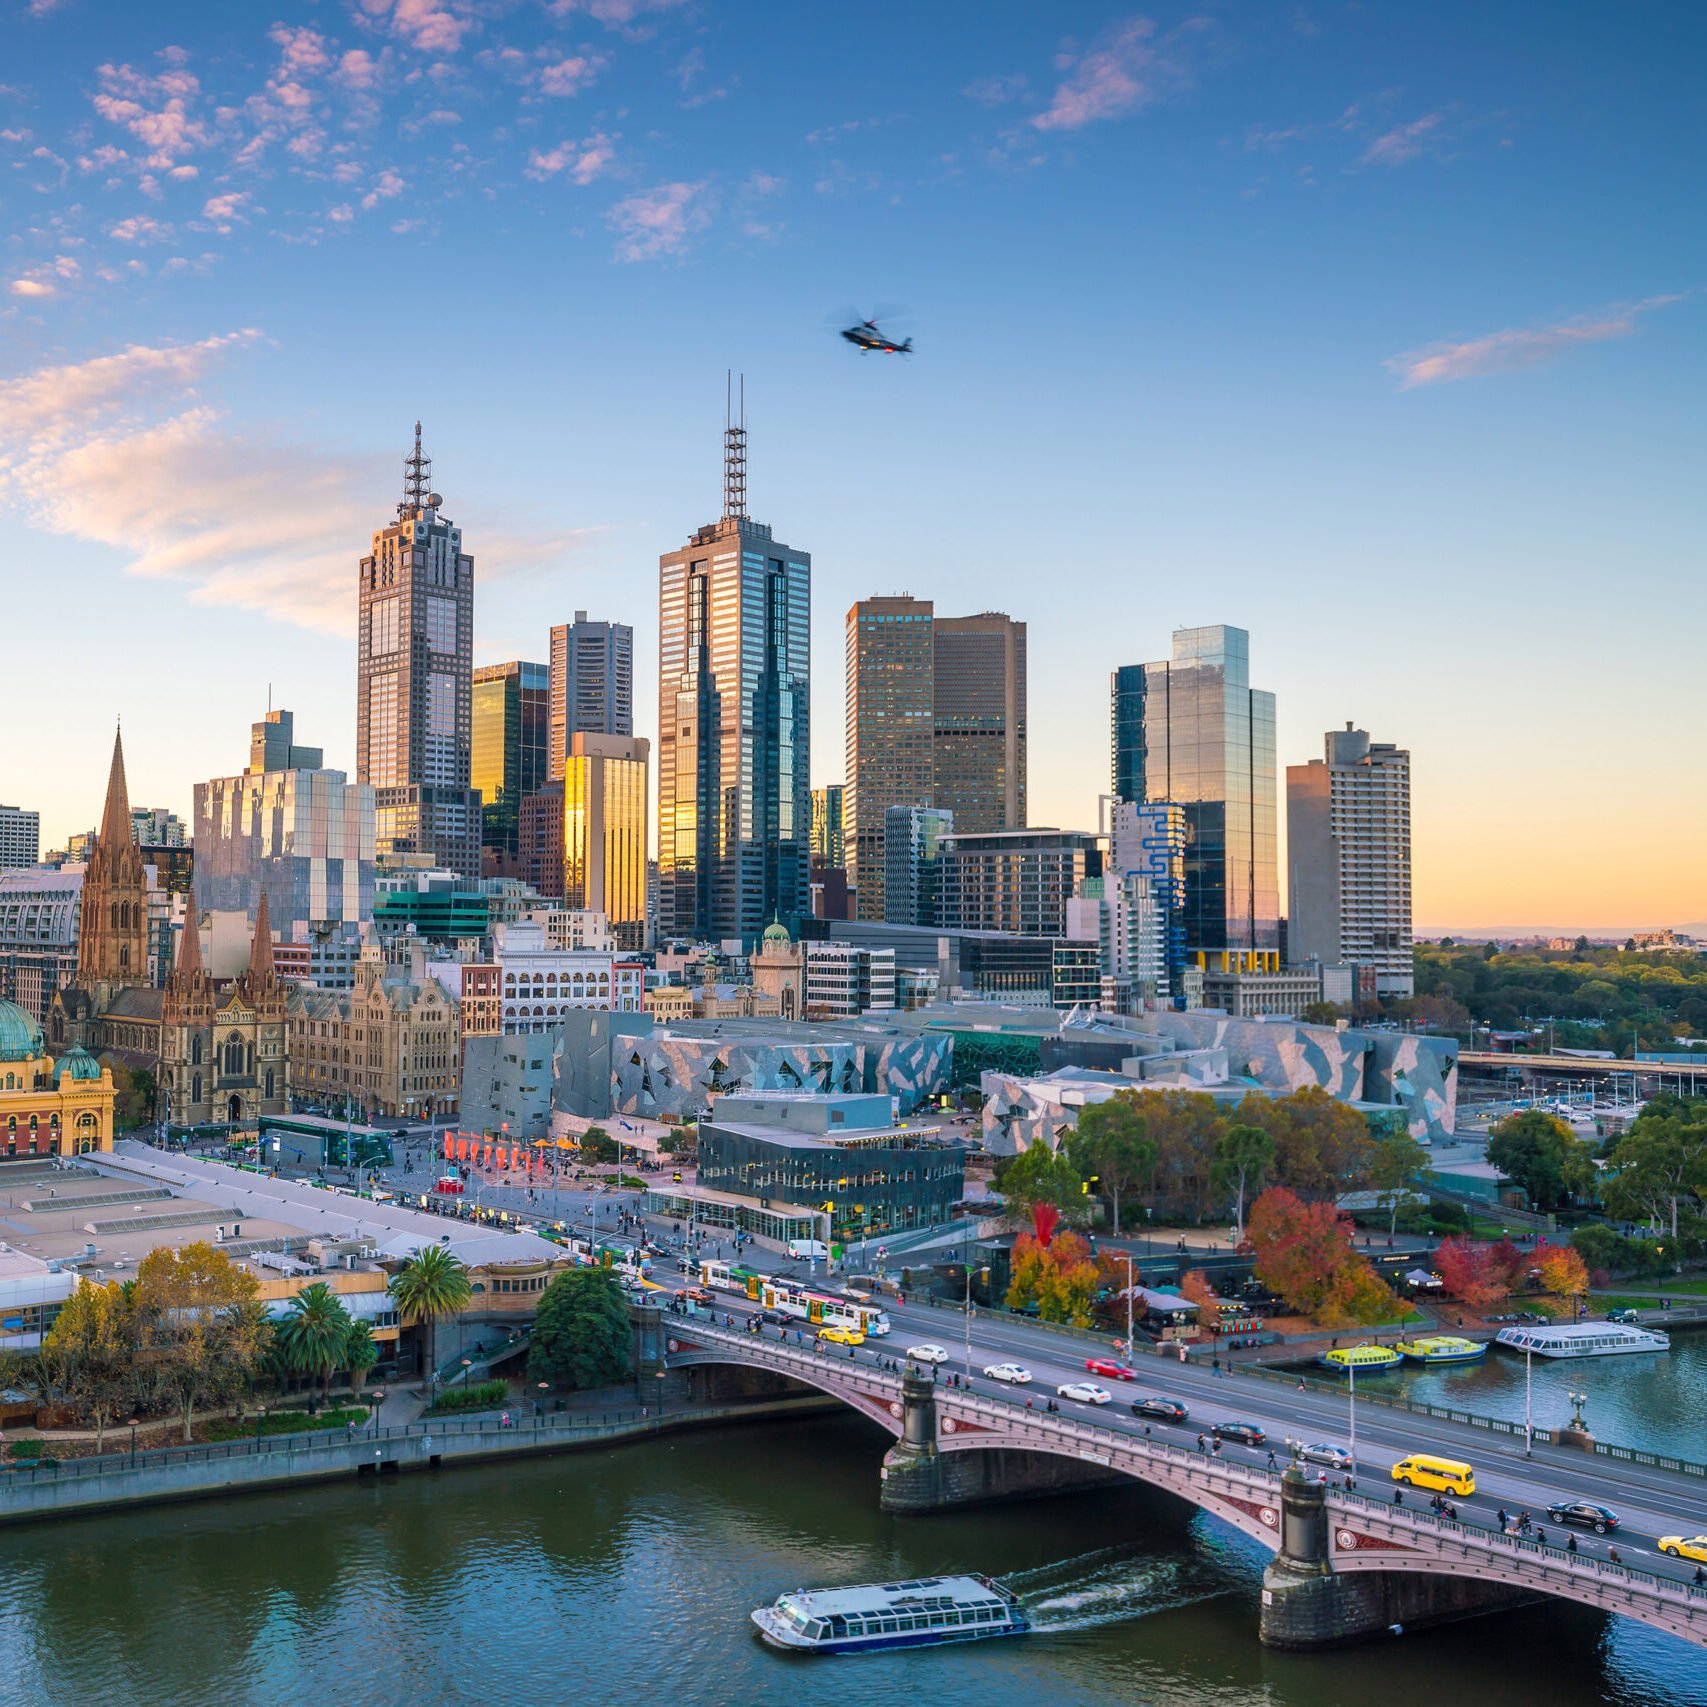
Melbourne city skyline at twilight in Australia
Melbourne tenants are already paying more
The September 2026 realestate.com.au Rental Report puts Melbourne’s median advertised rent at $600 a week, up 5.3% over the year.
That’s an additional $1,560 a year at the median, bringing the annual rental bill to $31,200.
These are advertised rents, so they reflect the market for people looking for a rental rather than an identical increase for existing tenants.
A property can remain standing and still leave the rental market
A common response to concerns about investors selling is that the house doesn’t disappear.
Of course it doesn’t, but its availability to tenants depends on who buys it and how they use it.
If another investor purchases the property and continues to rent it out, there may be little lasting change in rental supply. If an owner-occupier buys it, the property leaves the rental pool.
When the buyer is a renter becoming a homeowner, rental demand falls too, potentially offsetting that loss.
Now that’s an important qualification, and it means we can’t interpret the 40% listing figure as a 40% reduction in Melbourne’s rental stock.
However, the adjustment is rarely perfectly matched across suburbs, budgets and household types. A rental family home in one neighbourhood may be bought by someone who is leaving an apartment in a very different location.
For the displaced tenant, the practical issue is whether another suitable home is available near their children’s school, their work and their support network.
My concern is that weaker investor participation reduces the market’s ability to offer those choices for households that cannot afford to buy.
Encouraging new homes helps, but timing matters
The article also reports that nationally, investor loans for buying or building new homes rose 24% in the June quarter, even as total investor loans fell 9%.
Encouraging more housing is sensible, and shifting investment toward construction could increase supply over time.


However, a loan for a new dwelling is several steps away from a completed home with a tenant living in it.
The location, price and suitability of that new housing also matter. A future rental on the urban fringe can’t necessarily meet the immediate needs of a household seeking an established home close to work.
And at Metropole, we see investing in new-build properties in outer suburbs as having inferior long-term investment prospects.
We need a policy that retains rental homes while adding more
In my view, governments should give greater weight to keeping suitable existing homes in the rental market while accelerating additional supply.
That means predictable tax settings, workable implementation periods for new requirements, faster approvals for appropriate housing, and more social and affordable homes for people the private market struggles to serve.
Safe, well-maintained rental properties and fair treatment for tenants should remain central to that approach.
One option worth examining is targeted land tax relief tied to a commitment to provide a long-term rental at an independently benchmarked affordable rent, with safeguards against subsidising arrangements that would have happened anyway.
A carefully designed measure could make retaining a rental more attractive while giving tenants a direct benefit.
We should also track former rentals through to their eventual use, including how many remain tenanted and how many buyers leave the rental market. That would give policymakers a better measure of the impact than sale listings alone.
What this means for property investors
For investors with a long-term perspective, Melbourne’s changing rental market could create opportunities to buy well while other owners choose to sell.
Reduced competition from investors can give buyers more choice and greater negotiating room, while continued demand for rental accommodation could support rental income over time.
Of course, rising rents alone won’t make every property a good investment. The opportunity lies in selecting an investment-grade asset in a location people want to live, with enduring appeal to both tenants and future owner-occupiers.
I still believe Melbourne deserves a place on the radar of strategic investors. Its current challenges make careful property selection, realistic cash-flow planning and a sound financial buffer particularly valuable.
I’ve found that attractive buying opportunities often emerge during periods when confidence is subdued. Investors who understand the risks and have the capacity to hold through changing conditions can position themselves for the next phase of the market.
For existing owners, this is also a useful time to review your portfolio, assess your properties’ performance and ensure your finances support your longer-term goals.
If you’d like clarity about how these changes affect your position, why not speak with a Wealth Strategist at Metropole. We’ll help you look at your property investments within the context of your finances, goals and stage of life, so you can make informed decisions about your next steps.
Whether you’re considering your next purchase or reviewing the properties you already own, a personalised Strategic Property Plan can help you move forward with greater confidence and build wealth that supports your family for years to come. Click here now and lock in a time for a chat.