
Key takeaways
Property value is driven mainly by the land, and well-located land keeps getting scarcer
Australia added 392,700 people in the year to March 2026, while new housing supply continues to fall short
Location, lifestyle, character and gentrification explain why some homes consistently outperform
Interest rates move prices in the short term but don't change what makes a property valuable
In today's softer market, the gap between investment-grade homes and average stock is where wealth is made or lost
This month the Reserve Bank lifted the cash rate to 4.60%, its fourth increase this year and the highest level since late 2011.
Sydney home values are now around 7% below their February peak, the top end of the Melbourne and Sydney markets has fallen more than 10%, and plenty of investors are quietly wondering whether property is still the wealth builder it has always been.
Yet Australian residential real estate is still worth over $12 trillion, and over the years, I've watched values dip and recover more times than I can count.
The reason property keeps coming back lies in a handful of factors that make real estate valuable in the first place. Understanding them is what separates investors who build real wealth from those who simply own a few properties.
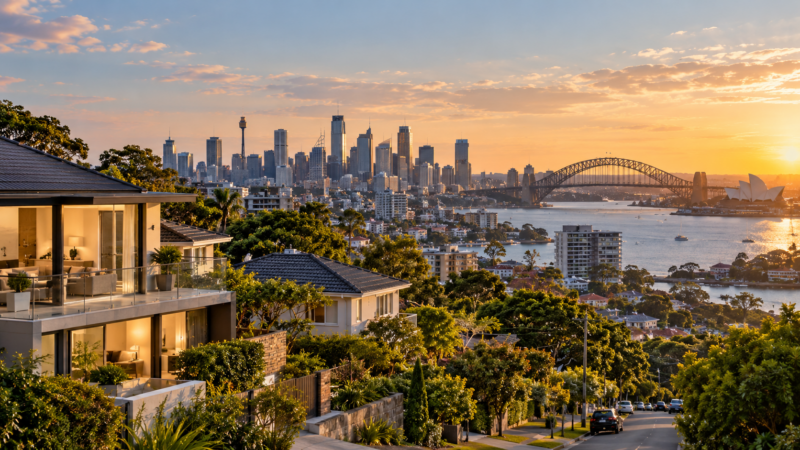
Value is a tricky thing to pin down
We all know that gold, diamonds, oil and even saffron are valuable commodities, thanks to their scarcity, desirability or the fact that we need them to go about our lives.
It's the balance between supply and demand that drives up their value, because when enough people want something badly enough, they'll pay the price.
Property works the same way, although it taps into some of our strongest human needs and desires - security, safety, status, a sense of achievement, and something to leave behind for our children.
We live in a country with vast open spaces, yet we cling to the major coastal capitals and treat the inner and middle-ring suburbs of Sydney, Melbourne and Brisbane as hallowed turf we can only hope to live on one day.
It's worth separating price from value for a moment, because they behave very differently.
In the short term, prices get pushed around by interest rates, credit availability, consumer confidence and government policy, which is exactly what we're seeing right now.
Over the long term, value is determined by a handful of fundamentals that hold true in the most buoyant and the most subdued markets, so let's look at them.
1. We keep adding people faster than we add homes
According to ABS figures, Australia's population grew by 392,700 people (1.4%) over the year to March 2026, taking us to 27.9 million.
That's like finding room for a new Tasmania roughly every 18 months, or a city the size of Darwin every five months or so.
Around three-quarters of that growth came from overseas migration, with Western Australia growing fastest at 2.1%, while Victoria and Queensland both grew by 1.6%.
Victoria alone added 109,500 people last year, which works out to more than 2,000 new residents every week who all need somewhere to live.
Meanwhile, we're simply not building enough homes.
The National Housing Accord set a target of 1.2 million new homes over five years to June 2029, but the latest report from the National Housing Supply and Affordability Council shows only about 308,000 have been completed so far, and the Council now expects the target to be reached only by the end of 2030.
There is a record number of dwellings under construction, but most new supply is either high-rise towers in and around our CBDs or house-and-land packages on the outer fringes of our cities.
What remains in short supply is the "missing middle" - townhouses, villa units and boutique apartments in the established middle-ring suburbs where most people want to live. That scarcity keeps showing up in the prices of these homes.
2. The land does the heavy lifting
A building ages, needs maintenance, and eventually goes out of fashion, while the land underneath it tends to appreciate because nobody is making more of it in the places people want to live.
That's why the value of a property is driven primarily by the value of its land, and why, in any given location, larger blocks will usually be worth more than smaller ones.
It's also why I look for properties with a high land-to-asset ratio. Even when buying apartments, I prefer boutique blocks with fewer units, where each owner holds a more meaningful share of the land.
Rising construction costs since the pandemic have added another layer, because when it costs more to build a new home, the established homes that already exist in good locations become more valuable too.
3. Not all land is created equal
Sure, size matters, but what really matters is where that land is located.
In general, land closer to the CBD or the water, or within an easy walk of train stations and public transport, is more sought after and therefore more valuable.
Just look around your own neighbourhood and you'll notice that not all spots are considered equal. Some pockets are more sought after, some streets are more attractive, and one end of a street can even be more desirable than the other.
School zones are a good example, with Cotality research showing that families are paying six-figure premiums to buy within the catchments of top public schools.
A safe place to sleep at night is only part of the picture, because people also want to be close to amenities, their workplace, good schools, or the beach, and they're prepared to pay for the privilege.
These homes tend to be in established areas where vacant land is non-existent, which adds scarcity to the equation.
- Also read:Latest Property Price Forecasts. Australian Property Market Outlook 2026-2027: Navigating a Market Correction

- Also read:Brisbane Property Market Forecast [2026 & Beyond] – What The Olympics Decade Means for Investors.
- Also read:Melbourne property market forecast for 2026 & 2027 | Separating the fundamentals from the sentiment
- Also read:Sydney property market forecast for 2026 and 2027 | Why the short-term softness is a long-term opportunity
- Also read:Home Prices Down Again Over September – But Not as Much | Latest Property Market Stats

If only a handful of homes are within walking distance of your favourite surf break and plenty of buyers are hoping to snap them up, competition will push prices higher.
It's much the same around the café and shopping strips of our capital city inner suburbs, where more of us are happy to trade space for place, swapping the big backyard for a courtyard or balcony so we can live close to the action.
We're seeing this play out right now, with more buyers dealing with affordability pressures by moving to townhouses and apartments rather than moving further from the CBD.
Because accommodation in these locations is scarce, it becomes more valuable over time as people with higher disposable incomes are able and willing to pay a premium to live there.
5. Character, style and a little bit of scarcity
Period, Federation and Art Deco homes, full of architectural features and charm, are rarer and more sought after than cookie-cutter new builds.
As a result, they tend to appreciate faster than the lookalike properties surrounding them.
Home buyers will usually pay more for a home with character, a level of scarcity or a twist - something special that can't easily be replicated down the road.
This is one reason I'm cautious about brand-new off-the-plan stock, because a building that looks just like those on either side of it has very little scarcity value to rely on.
6. Infrastructure changes the map
Improving the infrastructure around a property makes it more accessible and more liveable, which increases its value.
Think of new rail lines such as Melbourne's Metro Tunnel and Sydney Metro, freeways that shorten trips to the CBD or major employment hubs, or new shopping centres and health precincts.
One word of caution, though, because the benefit of a major project is often priced in well before the ribbon is cut, and buying purely on the promise of infrastructure in an area without other demand drivers is speculating rather than investing.
7. Gentrification lifts whole suburbs
One of the biggest changes in our capital cities over the past 50 years has been gentrification - the shift in the socioeconomic makeup of a suburb.
As more affluent residents move in, they renovate older houses or build new ones, and in doing so they pull up the value of the neighbouring properties too.
These households also have higher incomes and greater borrowing capacity, which means they can keep paying more for homes in these suburbs over time.
Suburbs in the early to middle stages of gentrification have been among Australia's best performers for decades, and I expect that to continue.
8. Owner-occupier appeal matters more than ever
Only a few years ago, investors were a major force in our property markets, accounting for close to half of all new home loans in Sydney at one point.
That's changing, with Cotality figures showing investor lending fell 10.2% in the June quarter. The tax changes announced in this year's Federal Budget - including restrictions on negative gearing for established properties from July 2027 and the replacement of the 50% CGT discount with indexation - are likely to keep some investors on the sidelines.
This means owner-occupiers will make up an even larger share of buyers in the years ahead, and the properties that hold and grow their value best will be the ones owner-occupiers want to live in.
Tax concessions can support a good investment, but they've never been able to rescue a poor one, so the location and quality of the asset has to come first.
9. Interest rates move prices, not fundamentals
There's no doubt this month’s rate rise will add pressure on household budgets and buyer confidence.
Selling conditions have already softened, with vendor discounts across the capitals widening to 4.2%, total listings up 18.1% on a year ago, and auction clearance rates around 50% since early June.
It's worth noting, though, that none of this changes how many people need a home, how scarce well-located land is or where people want to live.
What a softer market does change is your negotiating position, because financially prepared buyers now have more choice and bargaining power than they've had in years.
The key is to ensure you have enough financial buffer to hold your properties comfortably through this part of the cycle. If you can hold quality assets long enough, time and growth do the heavy lifting.
The bottom line
Like most things in life, it's supply and demand that determine a property's value.
Looking ahead, Australia's growing population, our increasing national wealth and our desire to live in a select number of locations in our major capital cities will continue to underpin property values, regardless of what the Reserve Bank does over the next few months.
The catch is that these fundamentals don't apply equally to every property, and only a small percentage of the homes on the market today tick all the boxes that make real estate valuable over the long term.
If you'd like help identifying which properties will outperform through the next cycle, the team of independent property strategists at Metropole can build a personalised plan to help you grow, protect and pass on your wealth – please click here now and lock in a time for a chat with one of our Wealth Strategists.