
Key takeaways
Comparing interest rates alone overlooks mortgage size and the income available to repay it.
Today’s buyers face two substantial hurdles: accumulating a deposit and servicing the loan.
ABS data shows home ownership has declined across successive generations when compared at the same age.
Buyers can adapt their strategy, while governments need to improve housing supply and affordability.
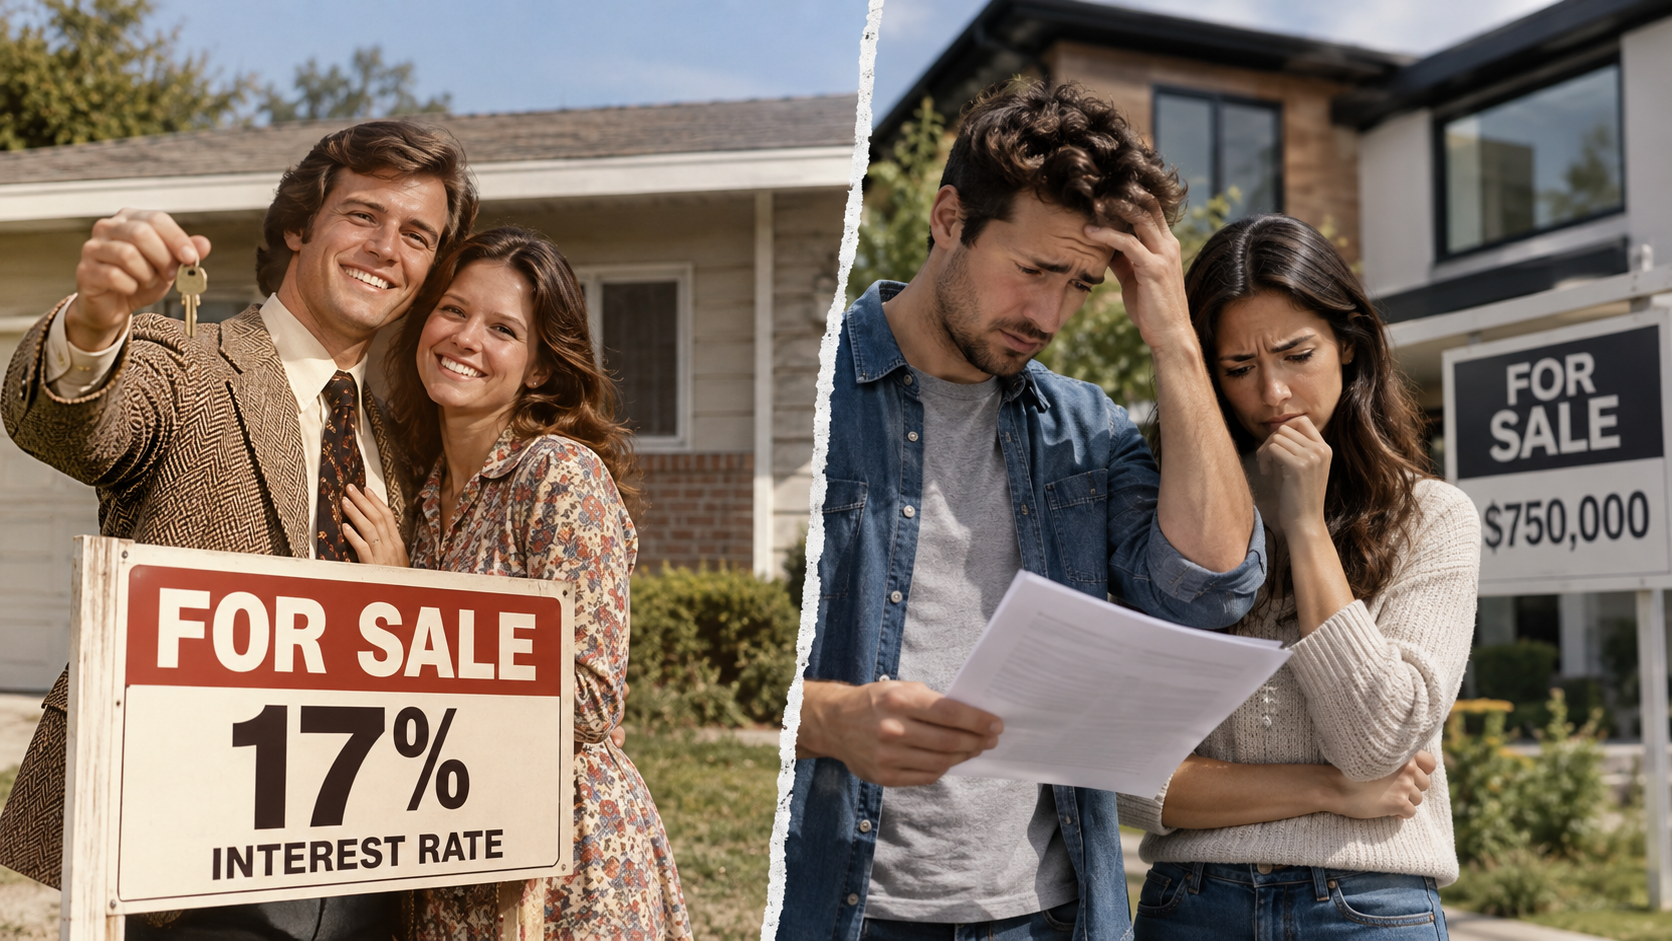
If you’ve ever told your children that buying a home was harder when mortgage rates reached 17%, the latest research might make you reconsider.
Those interest rates were painful, and many Australians made considerable sacrifices to keep their homes.
But today’s buyers face a combination of larger loans, higher deposit requirements and housing costs that make getting started much more difficult.
In other words, Baby Boomers should acknowledge how much the financial hurdles have changed.
Hard work and disciplined saving still matter, but younger Australians are applying those habits to a very different set of numbers.
What the mortgage comparison shows
Primara Research, working for HomeLoanRates.com.au, compared average new home loans and repayments against median full-time income in 1990 and 2026.
The comparison, reported by realestate.com.au, shows a higher repayment burden in every capital city despite substantially lower mortgage rates. realestate.com.au
| Capital city | Average new loan, 1990 | Repayments as share of income, 1990 | Average new loan, 2026 | Repayments as share of income, 2026 | Loan size increase |
| Sydney | $84,594 | 61% | $841,693 | 66% | 10 times |
| Brisbane | $58,127 | 46% | $751,001 | 59% | 13 times |
| Adelaide | $58,499 | 42% | $671,709 | 57% | 11 times |
| Melbourne | $67,864 | 49% | $664,145 | 54% | 10 times |
| Perth | $59,445 | 43% | $720,012 | 52% | 12 times |
| Canberra | $67,072 | 41% | $665,983 | 51% | 10 times |
| Hobart | $44,527 | 32% | $516,190 | 44% | 12 times |
| Darwin | $52,386 | 34% | $545,470 | 43% | 10 times |
Source: Primara Research for HomeLoanRates.com.au, as published by realestate.com.au. Multiples are rounded.
These figures compare repayments with an individual’s median full-time income, rather than total household income.
They illustrate the changing burden of a new loan, rather than the proportion of all households experiencing mortgage stress.
They also compare nominal loan amounts, so the dollar increase must be considered alongside income growth.
Why the 17% argument falls short
Anyone who lived through that period remembers the pressure of high interest rates, and acknowledging today’s difficulties takes nothing away from those experiences.
However, an interest rate tells only part of the story because the amount borrowed has a major influence on repayment.
For illustration, a $100,000 principal-and-interest mortgage at 17% over 30 years requires repayments of approximately $1,426 a month. An $800,000 mortgage at 6% over the same term requires approximately $4,796 a month.
These are illustrative calculations, rather than a historical affordability comparison, because incomes and living costs also changed.
Nevertheless, they demonstrate why a lower interest rate can coexist with a much larger monthly commitment.
In my view, older Australians sometimes remember the interest rate more clearly than the relationship between the purchase price, their deposit and their household income.
The deposit hurdle starts long before the mortgage
Much of the generational debate focuses on repayments, yet aspiring buyers must first accumulate enough money to enter the market.
The National Housing Supply and Affordability Council’s 2026 report estimates that a median-income household needed 11.2 years to save a 20% deposit in the December quarter of 2025. Its calculation assumes the household saves 15% of gross income each year.
This is a modelled affordability measure, not a prediction of how long every buyer will spend saving, but it shows the scale of the challenge.
Consider buying a hypothetical $900,000 home which requires a 20% deposit of $180,000, before allowing for applicable purchase costs and a financial buffer.
Saving that amount while paying rent can be difficult even for people with respectable incomes and sensible spending habits.
AIHW reports that rental affordability has deteriorated across most capital cities since 2015 as rental costs have grown faster than household incomes. That puts additional pressure on the money prospective buyers can set aside.
Telling young Australians to cut back on coffee may help their budgeting at the margin, but I believe it trivialises the size of the deposit they are trying to build.
Fewer Australians own homes at the same age
One of the strongest pieces of evidence comes from the Australian Bureau of Statistics, which compared generations at equivalent ages.
Among Australians aged 25 to 39, home ownership was 66% for Baby Boomers in 1991, 62% for Generation X in 2006 and 55% for Millennials in 2021.
- Also read:How much do buyer’s agents charge in Australia
- Also read:What laws do real estate agents have to abide by?
- Also read:The offer and acceptance process when buying a property
- Also read:Caveats: The hidden red flags smart property investors never ignore

- Also read:What property sellers have to disclose
This comparison is much more useful than comparing today’s young adults with retirees who have had decades to accumulate equity.
Millennials entering family formation later in life and making different lifestyle choices To previous generations obviously influences when people buy, so affordability can’t explain every difference.
Nevertheless, the downward trend reinforces the concern that ownership is becoming harder to achieve.
The ABS also found that Baby Boomers aged 25 to 39 in 1991 were three times as likely to own their homes outright as Millennials of the same age in 2021.
That has implications for how long people carry debt and the financial flexibility they have later in life.
Family wealth can change the starting point
A substantial gift from parents can make the difference between buying sooner and spending several more years saving.
For families able to help, that can be a sensible use of accumulated wealth, provided the parents’ own financial security is protected.
However, it also means two young Australians with similar incomes and equally disciplined habits can have very different opportunities because of their family circumstances.
My concern is that access to home ownership can become increasingly dependent on existing family wealth.
Helping our children deserves careful planning, including clarity about whether support is a gift, a loan or a guarantee, and professional advice about the consequences.
Making borrowing easier has limits
Over the last couple of years, various government incentives have assisted first-time buyers getting into the market by reducing their deposit requirement, helping buyers who earn enough to service a mortgage but struggle to accumulate savings.
Yet a smaller deposit generally leaves a larger loan to repay, so deposit assistance and repayment affordability need to be considered together.
There is also a broader policy issue: increasing buyers’ purchasing power while housing supply responds slowly obviously adds competition for the available homes.
This has pushed up home prices in certain price brackets and locations, making it harder for the next round of first-home buyers.
What can younger buyers do?
A good starting point is acknowledging the challenges and working on a plan, rather than discouraging buyers from entering the housing market.
One practical adjustment is to recognise that your first home won't be your eventual family home, and to consider a smaller property like a villa unit, townhouse, or established apartment.
For some, rentvesting may also deserve consideration, although the rental income, ownership costs, tax treatment and borrowing requirements need to be assessed carefully following the recent Federal Budget tax changes.
Above all, I would encourage buyers to work backwards from a repayment they can sustain while retaining a buffer, rather than organising their lives around the maximum loan offered.
A harder starting point calls for a different approach
I believe the evidence supports the view that entering the housing market is harder for many Australians today than it was for Baby Boomers.
There's no doubt previous generations faced real challenges, but today’s younger buyers face deposit and debt burdens that require serious consideration. That's what we do at Metropole when we help home buyers enter the market.
Why not click here, find out how we help home buyers, and organise a time for a chat to discuss your options?
There are still achievable paths to home ownership, although they may involve different properties, different locations and a more gradual progression.
Recognising that reality allows families, buyers and policymakers to have a more useful conversation about how to improve their opportunities.
As buyers' agents we have no properties to sell. We work for one person - you.
The selling agent is legally working for the vendor, and knows at least five things about that property they don't want you to know. We put an experienced professional on your side of the table to level the playing field.